

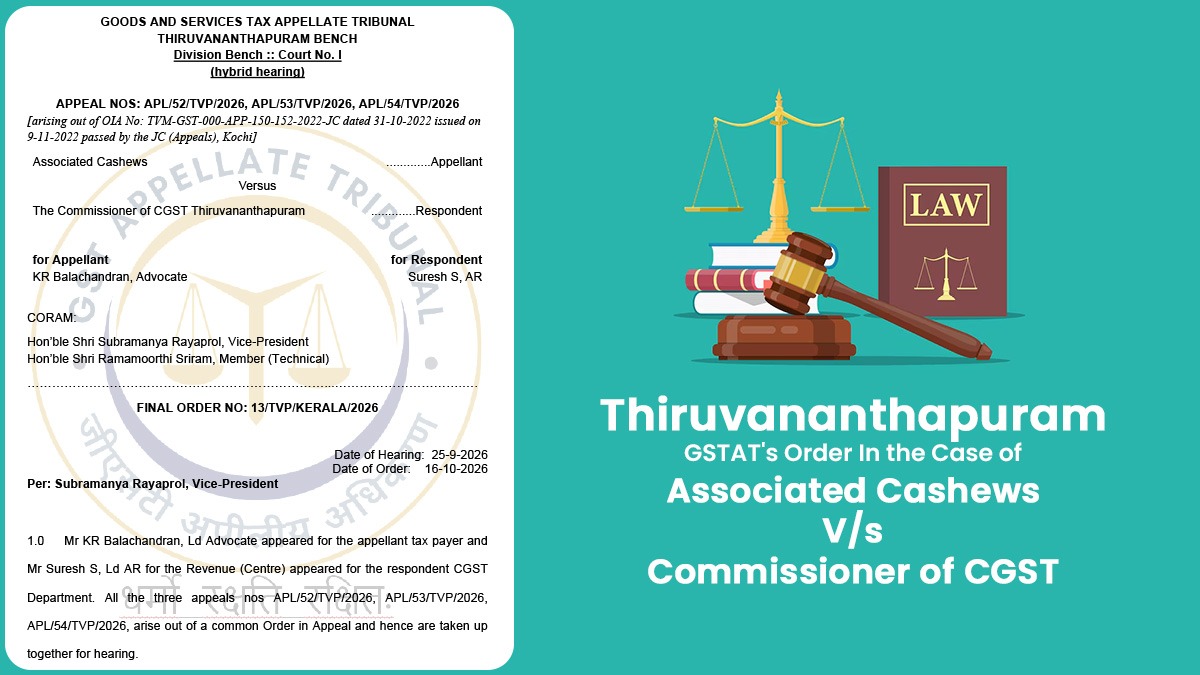
The Thiruvananthapuram bench of the Goods and Services Tax Appellate Tribunal (GSTAT) has allowed a refund of approximately Rs 19.79 lakh to a cashew exporter, ‘Associated Cashew’. This amount had been paid twice as Integrated Goods and Services Tax (IGST). The Tribunal stated that a refund of excess tax paid cannot be denied on the grounds of a clerical error made in the GST returns.
A Bench comprising Vice-President Subramanya Rayaprol and Technical Member Ramamoorthi Sriram said that the GST department cannot retain tax collected twice when the taxpayer was not lawfully required to make the additional payment. It stated that:
“The clerical mistake which is on the face of record is a minor one and properly explained for which the appellant cannot be penalised by not refunding the amount paid in excess of what was due to be paid. There is no warrant for the Revenue authority concerned to retain the amounts found to have been deposited twice and reject the application for refund claimed by the appellant.”
This matter came to light when ‘Associated Cashews’ exported cashew kernels and paid 5% IGST. However, while filing its GSTR-3B return, the exporter inadvertently entered the export details under the column for domestic sales, instead of the column designated for exports.
The error prevented the customs system from automatically processing the tax refund. To solve the problem, the associated cashews paid the same IGST again and accurately entered the export information in a subsequent return. The authorities processed the refund for the second payment, but retained the original tax payment.
Afterward the associated cashews asked for a refund of nearly Rs 19.79 lakh asserting that it had paid the tax two times. The claim has been denied by the tax authorities on the ground that the exporter had earlier obtained a refund.
Recommended: GSTAT Mumbai Denies GST Refund, Holds Foreign Procurement Support Services as Import of Services
The Tribunal discovered that the authorities did not differentiate between the two payments. It said that the refund granted is only pertinent to the second payment, and the original amount remained with the department.
The exporter had specified the clerical error via supporting documents and reconciliation statements. It outlined that tax cannot be collected without the authority of law and that a procedural mistake cannot specify withholding money paid in excess.
The Bench placed reliance on the decision of the Orissa High Court in Rajendra Narayan Mohanty v. Joint Commissioner of State Tax and the Karnataka High Court’s decision in Merck Life Science Private Limited v. Union of India, which dealt with refunds of taxes paid inadvertently or in excess.
Subsequently, the GSTAT quashed the orders denying the refund claim and permitted all three appeals submitted via ‘Associated Cashews’, granting them the relevant relief.
| Case Title | Associated Cashews Vs Commissioner of CGST |
| Case No. | 13/TVP/KERALA/2026 |
| For the Petitioner | KR Balachandran, Advocate |
| For the Respondent | Suresh S, AR |
| GSTAT Thiruvananthapuram | Read Order |