

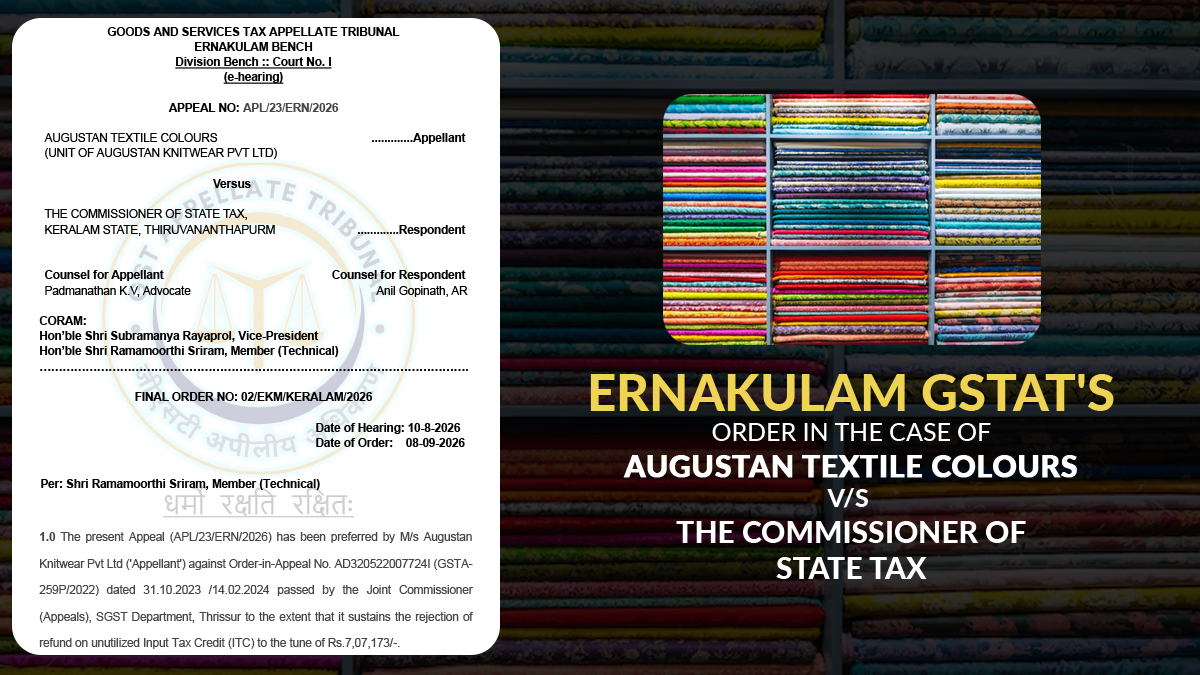
The Ernakulam Bench of the Goods and Services Tax Appellate Tribunal (GSTAT) has mentioned that the refund of the unused ITC cannot be refused based on ineligibility unless the credit is disallowed via proceedings under the provisions of the GST law.
A Bench, Vice-President Subramanya Rayaprol and Technical Member Ramamoorthi Sriram, permitted the appeal of Augustan Textile Colours, a unit of Augustan Knitwear Pvt Ltd, and quashed the refusal of Rs 7.07 lakh from its refund claim. The Tribunal mentioned that-
“the fundamental legal principle remains that when there are clear and distinct statutory provisions governing the determination of ITC eligibility and refund of unutilized ITC, refund of unutilized ITC cannot be denied on the ground of non-eligibility without a formal proceeding to disallow such ITC under the relevant provision”
Augustan Textile Colours Company manufactures textiles. Its inputs attracted 18% GST, whereas its outward supplies were taxed at 5%, resulting in an accumulation of ITC due to an inverted duty structure.
For the period July to September 2019, the appellant claimed a refund of Rs.18.41 lakh. The adjudicating authority rejected Rs. 9.72 lakh and sanctioned the remaining amount. Afterwards, the first appellate authority granted partial relief of Rs. 2.64 lakh but upheld the rejection of Rs. 7.07 lakh.
The appellant before the Tribunal mentioned that the SCN cited that the refund was not considered because of a “wrong ITC claim”. It did not furnish invoice-wise details or mention why the credit was not eligible.
The Tribunal found the notice to be vague, noting that it failed to specify the grounds on which the Input Tax Credit (ITC) was proposed to be denied.
It cited the Supreme Court’s judgment in the case of Commissioner of Central Excise, Bangalore vs. Vrindavan Beverages (P) Ltd., which held that a ‘show-cause notice’ should clearly state the allegations so that the taxpayer can effectively present their defence.
It observed the rejection of ITC by the first appellate authority on the ground of not using the goods and services in furtherance of business. This reason was not shown in the SCN. The Bench held that the proceedings were invalid from the SCN stage itself. It said that-
“even at the SCN stage itself, the present proceedings are vitiated on account of being vague and lacking details, thus depriving the tax payer of a proper opportunity to meet the allegations indicated in the SCN”
Furthermore, the Tribunal observed that the First Appellate Authority went beyond the scope of the ‘Show Cause Notice’ and based its decision on grounds that had never been put to the appellant, thereby violating the principles of natural justice.
It placed reliance on Paragraphs 20 and 21 of Circular No.125/44/2019-GST, which furnishes that where the refund is proposed to be cancelled based on the ineligible ITC, proceedings under Section 73 or 74 should be complied with for such ITC recovery.
The Bench u/s 54(3) mentioned that the refund proceedings could not be utilised to identify the ITC eligibility when no proceedings u/s 73 or 74 had been initiated to disallow the credit.
The Court held that unless an order disallowing the ITC under Section 73 or 74 is issued, the credit availed by the appellant must be treated as valid. The Court also noted that no such proceedings had been initiated against the appellant. The Court stated:
“We find that under the statute, any determination of the eligibility or otherwise of an input tax credit is permissible only under section 73/ 74. There cannot be any disallowance of input tax credit dehors the above provisions. The natural corollary to the above statement is that until and unless an order has been passed under section 73 / 74 disallowing the input credit taken, the input credit is presumed to be in order. In the instant case, no such proceedings been initiated against the appellant”
Important: GST Impact on Textile Industry in India
Therefore, the GSTAT permitted the appeal and quashed the portion of the appellate order, keeping the refusal of Rs 7.07 lakh refund with consequential relief.
| Case Title | Augustan Textile Colours vs. The Commissioner of State Tax |
| Case No. | APL/23/ERN/2026 |
| Counsel for Appellant | Padmanathan K.V |
| Counsel for Respondent | Anil Gopinath |
| Ernakulam GSTAT | Read Order |