

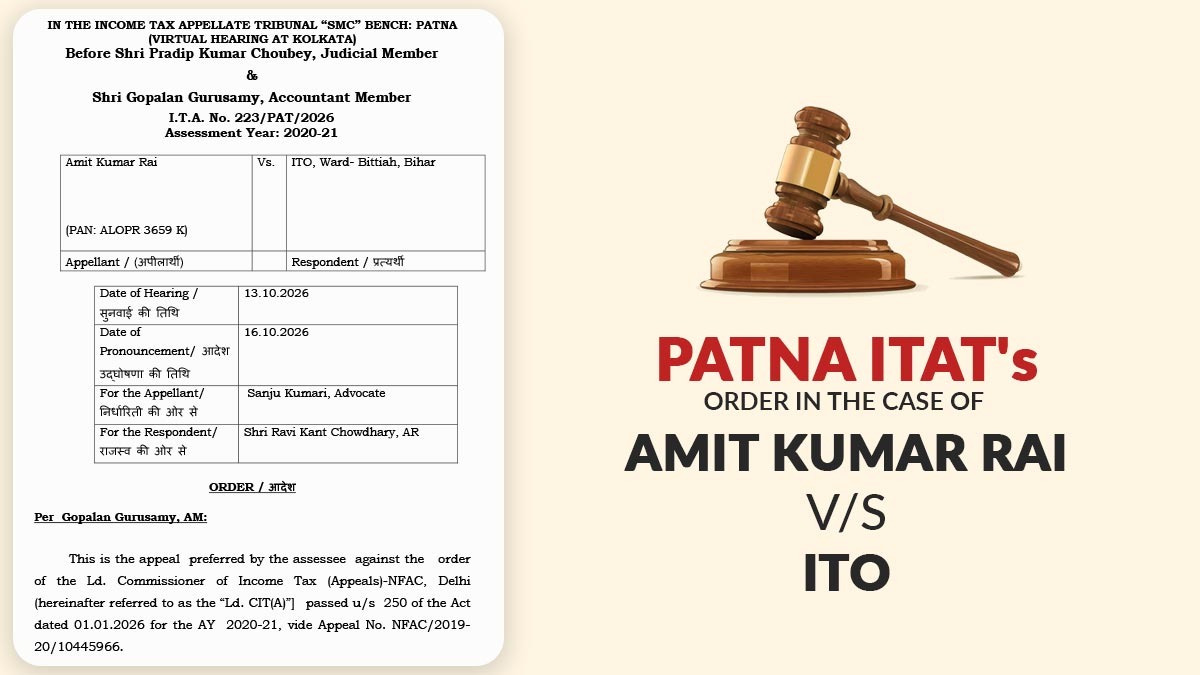
The Taxpayer, Amit Kumar Rai, had submitted the Income Tax return for AY 2020-21, reporting a total income of Rs 3,36,240. On the grounds of information that he had purchased immovable property jointly with Rubi Rai and Chandra Mohan Ojha, the AO initiated reassessment proceedings under section 147 of the Income Tax Act.
The data shows that the taxpayer had paid Rs 5 lakh in cash for the property, and an additional amount of Rs 35 lakh had been paid by Chandra Mohan Ojha on his behalf. In the reassessment proceedings, the taxpayer did not furnish an adequate explanation for the source of the cash payment and the amount paid on his behalf.
Consequently, the AO made an addition of Rs 5 lakh u/s 69A of the Act, considered Rs 35 lakh as a ‘deemed gift’, and, in the absence of supporting evidence, disallowed the taxpayer’s claim for a deduction of Rs 1,50,000 under section 80C. The CIT(A) upheld these additions and disallowances.
After considering the arguments of the parties, the Tribunal found that while the taxpayer had provided some information to the Assessing Officer (AO) regarding the source of the disputed investments, he failed to produce the necessary supporting documentation. Furthermore, the AO had not conducted any investigation or verification of the explanations provided by the taxpayer.
The Tribunal observed that the CIT(A) had asked the AO to check the year in which the sale was performed. The Tribunal considered such circumstances and stated that the case needs fresh analysis instead of being determined without factual verification.
Accordingly, the Tribunal quashed the assessment and directed the AO to conduct a fresh assessment after carrying out the necessary inquiries and verification.
| Case Title | Amit Kumar Rai Vs ITO |
| Case No. | I.T.A. No. 223/PAT/2026 |
| Assessee by | Sanju Kumari |
| Revenue by | Shri Ravi Kant Chowdhary |
| Patna ITAT | Read Order |