

The Bombay High Court has held that a hospital cannot be denied income tax exemption under philanthropic grounds simply for generating an operational surplus, charging patient fees, or collecting professional charges for consultant doctors.
The question is whether its actual operations and the utilisation of its funds demonstrate that its existence is solely for philanthropic purposes, rather than for profit-making.
A division bench of Justice B.P. Colabawalla and Justice Farhan P. Dubash quashed the orders passed by the Chief Commissioner of Income-tax rejecting Breach Candy Hospital Trust’s applications for approval u/s 10(23C)(via) of the Income-tax Act, 1961.
The provision does not include qualifying income received on behalf of a hospital from its total income, provided the hospital exists merely for philanthropic purposes rather than profit and obtains approval from the prescribed authority.
“The words ‘not for purposes of profit’ that are contained in sub-clause (via) of section 10(23C) require an examination of the purpose and actual conduct of the institution,” the court stated.
It has been clarified that under this provision, it is not mandatory for a hospital’s receipts and expenditures to be exactly equal at the end of every financial year. The court explained:
“The section itself contemplates income being applied or accumulated for the institution’s objects, subject to the statutory safeguards. A surplus can nevertheless be evidence of a profit purpose, particularly where the pattern of receipts, charges, expenditure and deployment supports that inference. Its existence is relevant, but not conclusive.”
Read Also: Bombay HC Rules IT Department Need Not Wait for Certified Copy of Digitally Signed Order
The Court applied the test to the activities of the Hospital, financial arrangements and use of income, carrying that a surplus alone could not specify that it operated for profit.
The dispute originated when the Chief Commissioner of Income Tax rejected the hospital’s exemption applications across multiple assessment years via separate orders issued on April 15, 2010 (AY 2002-03 to 2010-11) and September 28, 2012 (AY 2011-12 onwards).
The Court concluded the Hospital operates only for philanthropic purposes and not for profit, and thus it qualified for statutory tax approval/exemption, as retaining a financial surplus or investing in advanced infrastructure does not establish a commercial motive so long as funds are reinvested into healthcare services without private diversion.
Furthermore, facilitating consultant fee collections while retaining a 10% administrative fee represents a standard service payment rather than a profit distribution, and because Section 10(23C)(via) sets no fixed statutory quota for free or concessional treatment relative to gross receipts, a lower expenditure percentage on care for poor patients cannot, by itself, disqualify the hospital from philanthropic status.
The Court set aside both orders and asked the income tax authorities, or the authority presently competent to grant approval, to approve the applications of the Hospital for Assessment Years 2002-03 to 2010-11 and Assessment Years 2011-12 to 2021-22. The approvals should be issued within 8 weeks of the judgment being uploaded on the website of the High Court.
Important: Karnataka HC: Healthcare Services Provided Through Partner Hospital Exempt from GST Levy
The court finalised the ruling in both petitions and ordered that there shall be no order as to costs.
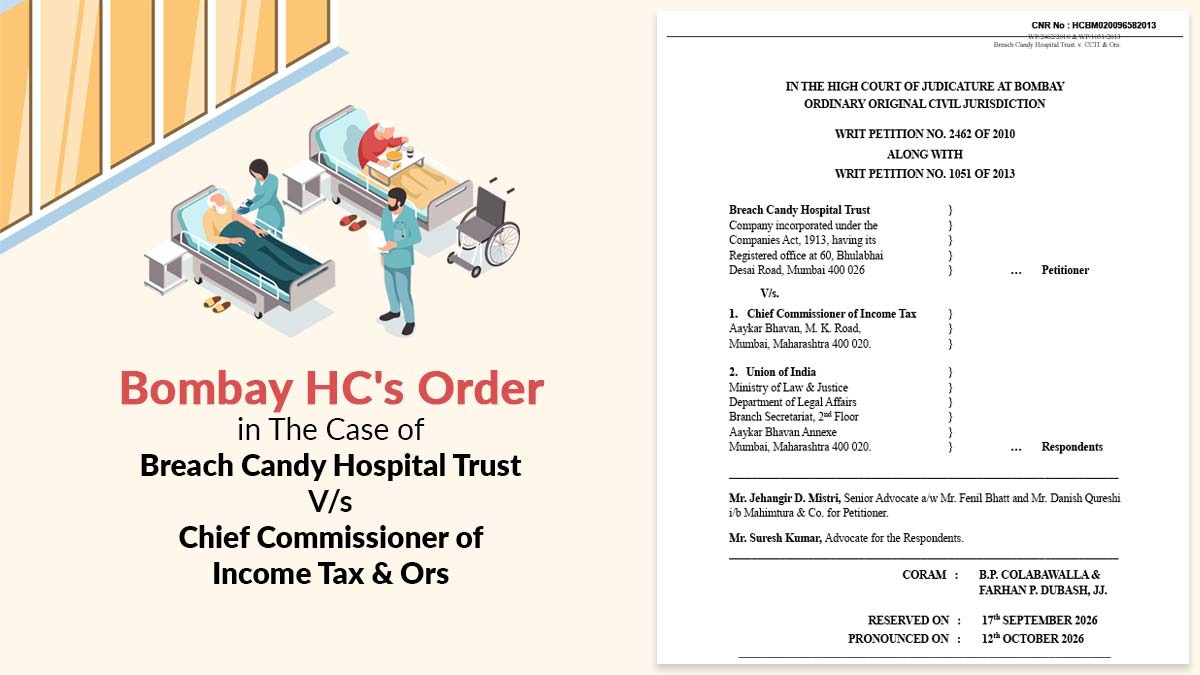
| Case Title | Breach Candy Hospital Trust vs. Chief Commissioner of Income Tax & Ors |
| Case No. | NO. 2462 OF 2010, Petition No. 1051 of 2013 |
| For the Petitioner | Mr Jehangir D. Mistri, Mr Fenil Bhatt and Mr Danish Qureshi |
| For the Respondents | Mr. Suresh Kumar |
| Bombay High Court | Read Order |