

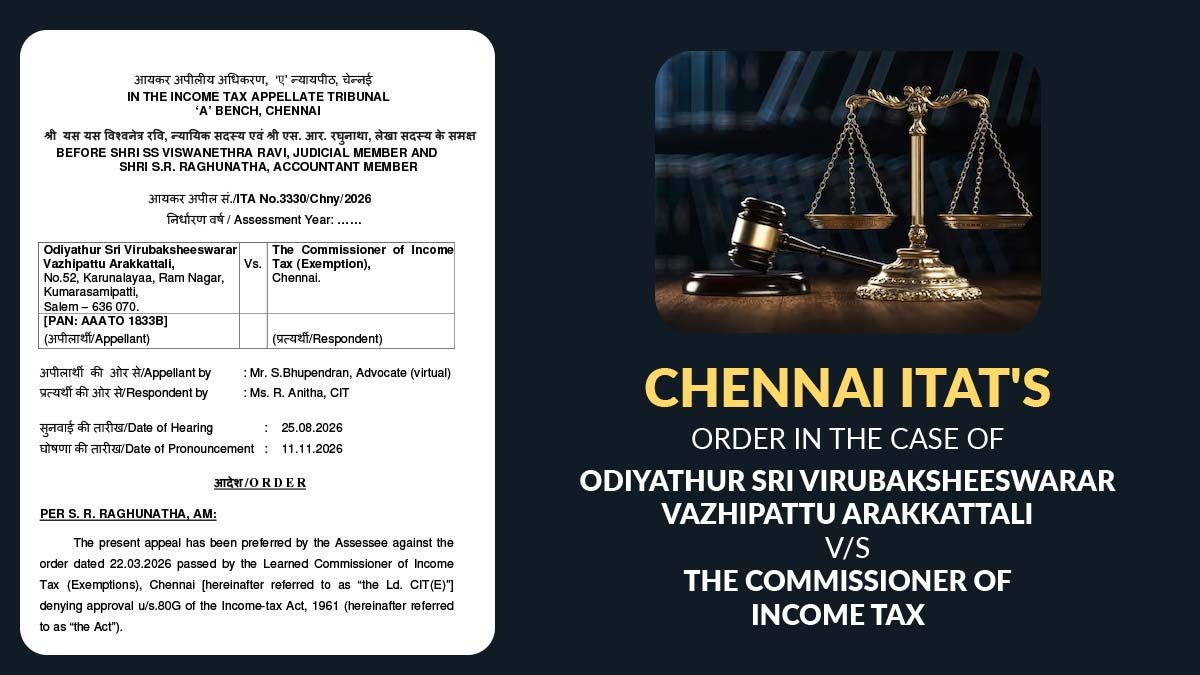
The taxpayer, Odiyathur Sri Virubaksheeswarar Vazhipattu Arakkattali, is a trust registered under section 12AB of the Income Tax Act, 1961, as a religious-cum-charitable trust.
Its stated functions included, in addition to temple administration and the maintenance of places of worship, providing food (annadan) to the poor and needy, offering medical assistance, supporting the education of economically disadvantaged groups, aiding the destitute, and carrying out other public welfare activities.
The taxpayer has submitted an application on 27/09/2025 in Form No. 10AB under clause (ii) of the first proviso to Section 80G(5), asking for the renewal of its approval u/s 80G.
The CIT(E) considered the religious-cum-charitable nature of the trust and the provisions of Section 80G(5), especially the restriction on institutions established for religious purposes. It rejected the application vide order dated 22/03/2026.
The Tribunal stated that Section 80G(5) stipulates the norms for approving an institution or fund. As per clause (ii), the document constituting the institution must not contain any provision for the use or transfer of its income or assets for purposes other than charitable objectives.
Read Also: ITAT Chennai Orders CIT(A) to Condone 315-Day Delay and Adjudicate Assessee’s Appeal on Merits
Furthermore, according to clause (iii), the objective of the institution must not be to benefit any particular religious community or caste.
Significantly, the Tribunal drew attention to Section 80G(5B). According to this provision, notwithstanding anything contained in Section 80G(5)(ii) or Explanation 3, if an institution incurs expenditure of a religious nature during the relevant previous year that does not exceed 5% of its total income, it shall be considered an institution to which Section 80G applies.
In this case, the CIT(E) failed to determine the accurate amount of expenditure incurred on the maintenance of ‘Bhavanam Koil’ and ‘Perumal Koil’, or to compare this expenditure against the trust’s total income.
Furthermore, the Tribunal did not examine the trust’s primary objectives and actual charitable activities, nor did it assess whether its objectives were, wholly or substantially, of a religious nature.
Important: Easy Guide to File Online ITR 7 Form for A.Y. 2026-27
Based on these findings, the Tribunal quashed the order dated 22/03/2026 passed by the CIT(E) and remitted the case for fresh consideration.
| Case Title | Odiyathur Sri Virubaksheeswarar Vazhipattu Arakkattali vs. The Commissioner of Income Tax |
| Case No. | ITA No.3330/Chny/2026 |
| Appellant by | Mr. S.Bhupendran |
| Respondent by | Ms. R. Anitha |
| Chennai ITAT | Read Order |