

The taxpayer, Asha Kiran Rastogi, had not submitted her income tax return for the AY 2012-13. As per the available data with the Income Tax Department, the AO initiated reassessment proceedings u/s 147 of the Income Tax Act, 1961, and issued a notice under section 148 dated March 29, 2019.
In the reassessment proceedings, the AO asked for an explanation concerning cash deposits of Rs 63,06,000 in the taxpayer’s bank accounts maintained with Punjab National Bank and Bank of Baroda.
Since the assessee failed to provide the necessary clarifications, the AO passed an assessment order on December 5, 2019, under sections 147 and 144 of the Act, making additions of Rs 63,06,000 and Rs 2,13,842, respectively.
Subsequently, penalty proceedings were initiated, which concluded with a penalty order dated January 27, 2022, under section 271(1)(c) of the Act. The CIT(A) dismissed the appeal. Before the Tribunal, the taxpayer explained that the delay of 1,580 days was neither intentional nor driven by any specific motive.
It was clarified that the taxpayer is a senior citizen with no taxable income and had updated their mobile number and email ID on the income tax portal.
The taxpayer argued that, due to these circumstances and a lack of awareness regarding the departmental notices, she was unable to participate in the assessment and appellate proceedings. Consequently, she requested that the delay be condoned and the matter be remanded to the Assessing Officer (AO) for fresh consideration.
The Tribunal held that, being a senior citizen, having no taxable income, changes to the registered mobile number and email ID, relocation from Ambala to Delhi-NCR, and the loss of property-related documents, all these constitute sufficient grounds for condoning the delay.
Accordingly, the Tribunal condoned the 1,580-day delay in filing the appeal. Consequently, the Tribunal quashed the orders of the CIT(A), as well as the assessment order dated December 5, 2019, and the penalty order dated January 27, 2022.
Read Also: CBDT Condones Delay in Filing Form 10AB for 80G Approval Renewal
After providing the taxpayer with a fair and adequate opportunity to present their case, these matters were remanded to the AO (Assessing Officer) for a fresh decision in accordance with the law.
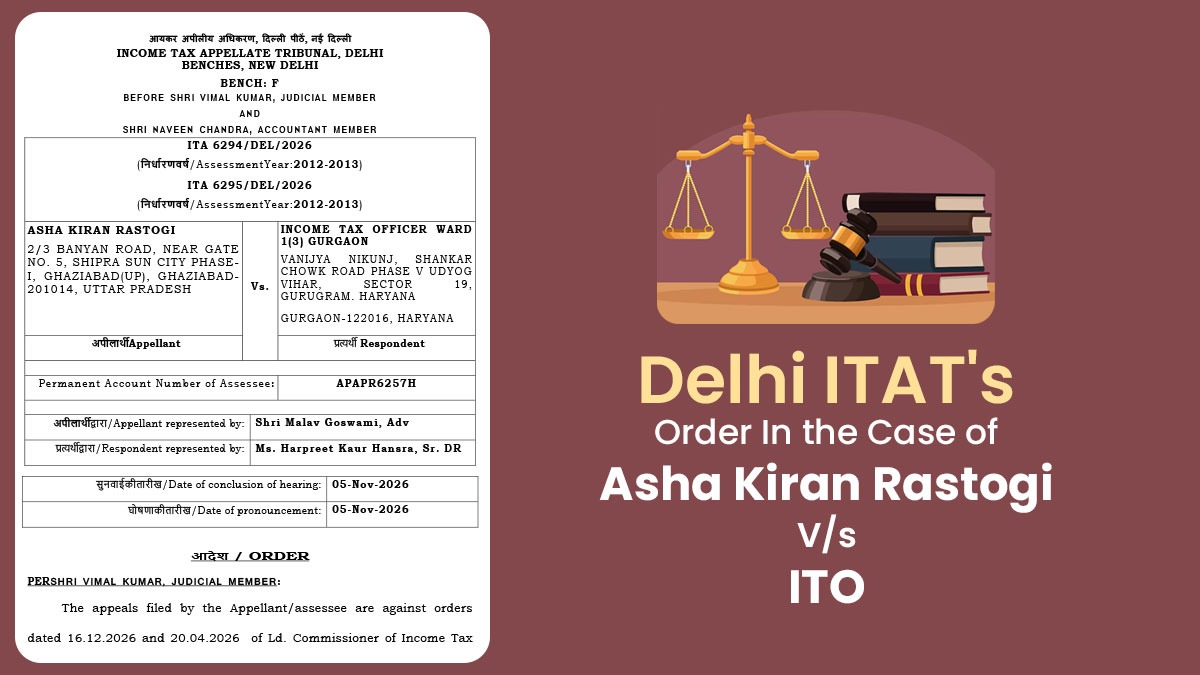
| Case Title | Asha Kiran Rastogi Vs ITO |
| Case No. | ITA 6294/DEL/2026 |
| Appellant by | Shri Malav Goswami |
| Respondent by | Ms Harpreet Kaur Hansra |
| Delhi ITAT | Read Order |