

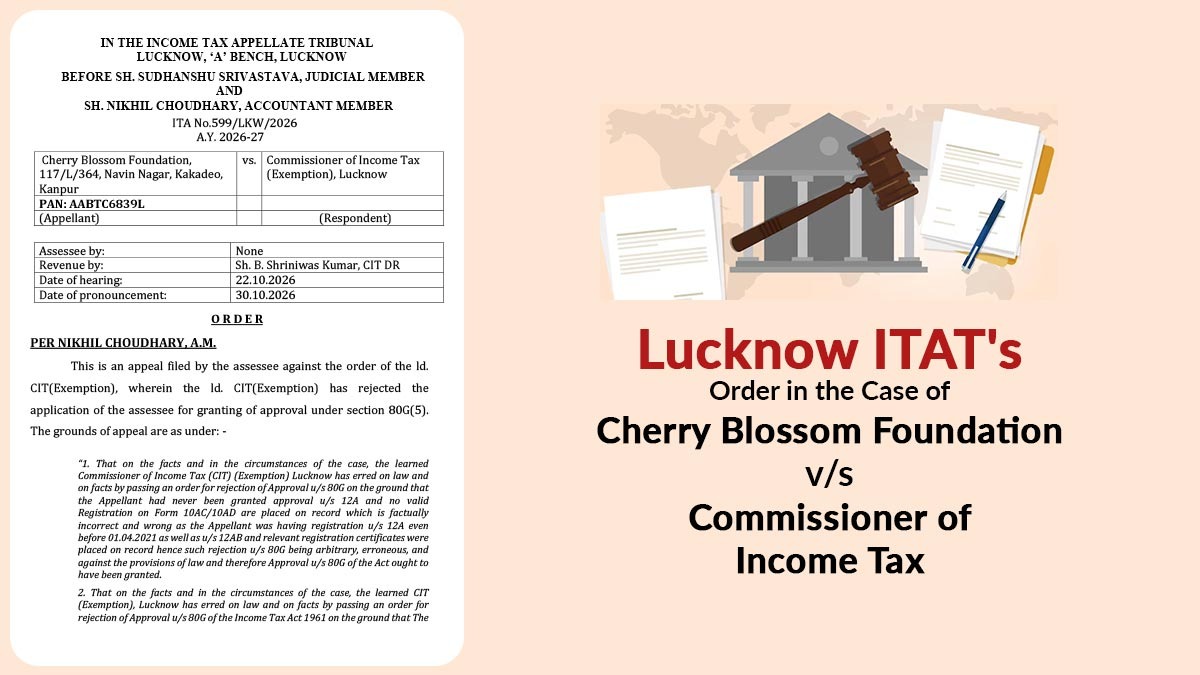
On 29/09/2025, the Cherry Blossom Foundation filed an application via Form No. 10AB seeking approval under Section 80G(5) of the Income Tax Act, 1961.
The CIT (E) did not accept the application on the grounds that the Foundation had never been granted approval u/s 12A, and that no valid registration certificate in the form of Form 10AC or 10AD existed on record.
The authority noted that the applicant did not fulfil the conditions stipulated u/s 80G(5)(ii) of the Act, as the income of the institution was obligated to be included in its total income under sections 11 and 12.
The tribunal analysed the documents and determined that the foundation had been provided provisional approval u/s 80G(5) in Form 10AC by the DIT (CPC) on 31/05/2021.
It also obtained provisional registration u/s 12A(1)(ac)(i) on the same date. The Tribunal observed that the provisional registration u/s 12A and approval u/s 80G(5) were correct from the AY 2022-23 to 2026-27.
Read Also: ITAT Lucknow Upholds Section 80IB(10) Deduction, Rejects Revenue’s Appeal Over Form 10CCB Filing
After considering the arguments presented in the paper book and by the departmental representative, the Tribunal found that the rejection order was likely based on a fundamental misunderstanding, namely, the assumption that the Foundation had neither obtained provisional approval in Form 10AC nor secured registration in Form 10AB before filing its application under Section 80G(5).
The Tribunal discovered that the Foundation had indeed obtained provisional registration u/s 12A and provisional approval u/s 80G(5), both of which are valid until the assessment year 2026-27.
Furthermore, the Tribunal noted that it appears the foundation has renewed its registration u/s 12A up to the AY 2036-37, although this remains to be confirmed.
Given these circumstances, the Tribunal deemed it appropriate and in the interest of justice to remand the matter back to the file of the CIT(E). Accordingly, the Tribunal allowed the taxpayer’s appeal for statistical purposes.
| Case Title | Cherry Blossom Foundation vs. Commissioner of Income Tax |
| Case No. | ITA No.599/LKW/2026 |
| Assessee by | None |
| Revenue by | Sh. B. Shriniwas Kumar |
| Lucknow ITAT | Read Order |