

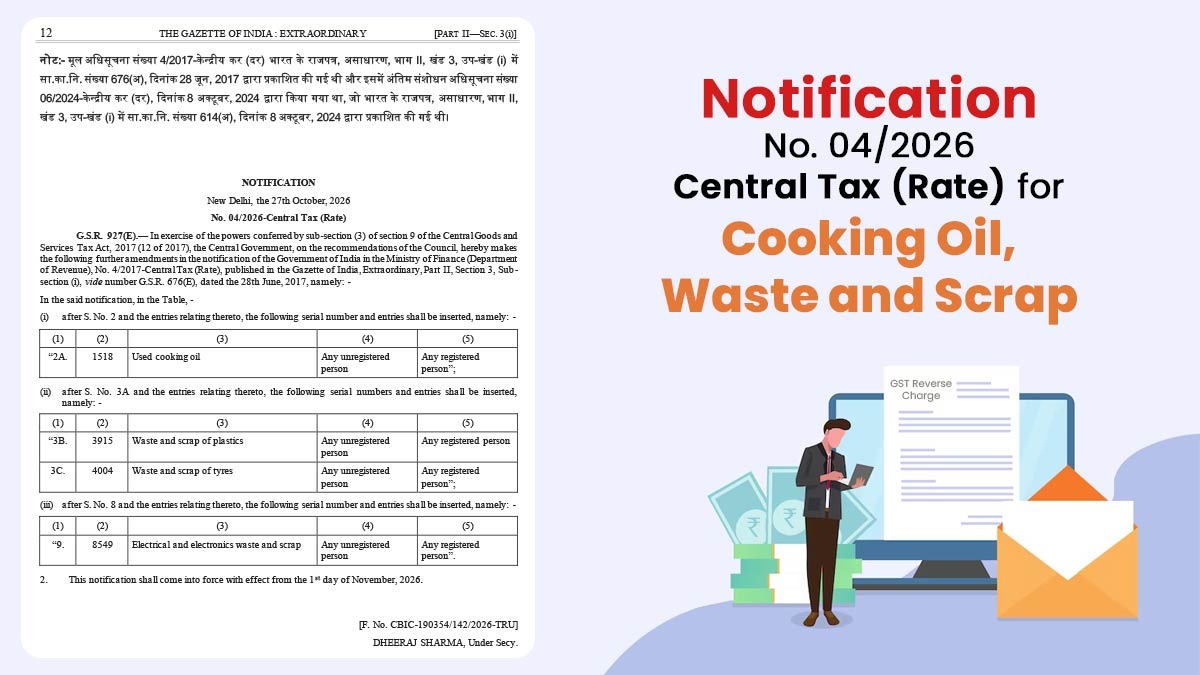
The Ministry of Finance, Department of Revenue, has issued Notification No. 04/2026-Central Tax (Rate), dated 27 October 2026, extending reverse charge coverage to four specified categories of goods supplied by unregistered persons to registered persons, w.e.f. 1 November 2026.
On the Council’s suggestions, the notification has been issued u/s 9(3) of the CGST Act, 2017. The notification revises Notification No. 4/2017-Central Tax (Rate), dated 28 June 2017.
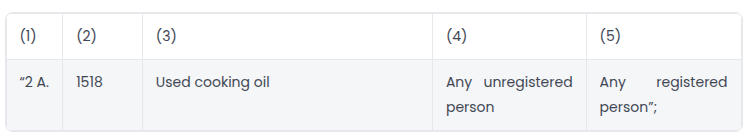
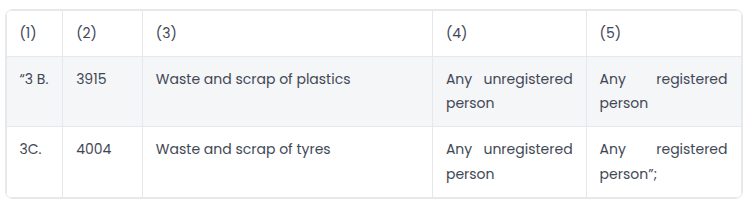
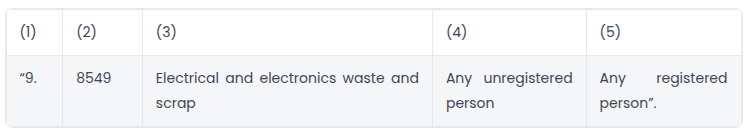
It inserts entry 2A after serial number 2 for used cooking oil under heading 1518; entries 3B and 3C after serial number 3A for waste and scrap of plastics under heading 3915 and waste and scrap of tyres under heading 4004, respectively; and entry 9 after serial number 8 for electrical and electronics waste and scrap under heading 8549.
Each new entry determines “Any unregistered person” as the supplier and “Any registered person” as the recipient. Consequently, for supplies falling under these entries, the registered recipient is liable for central tax under the reverse charge framework.
While this amendment mentions goods, tariff headings, and categories of suppliers and recipients, it does not specify any particular tax rate in its original text.
Important: Easy Guide to RCM (Reverse Charge Mechanism) in GST
Its final note provides details regarding the publication of the principal notification and identifies Notification No. 06/2024-Central Tax (Rate), dated October 8, 2024, as the preceding amendment.
In the Table of the said notification, the following amendments shall be made:
(i) After Serial No. 2 and its related entries, the following new serial number and corresponding entries shall be inserted:
(ii) After Serial No. 3A and its related entries, the following new serial numbers and corresponding entries shall be inserted:
Read Also: GST Rate on Sale of Scrap Materials with HSN Code
(iii) After Serial No. 8 and its related entries, the following new serial number and corresponding entries shall be inserted:
Read Notification No. 04/2026-Central Tax (Rate)