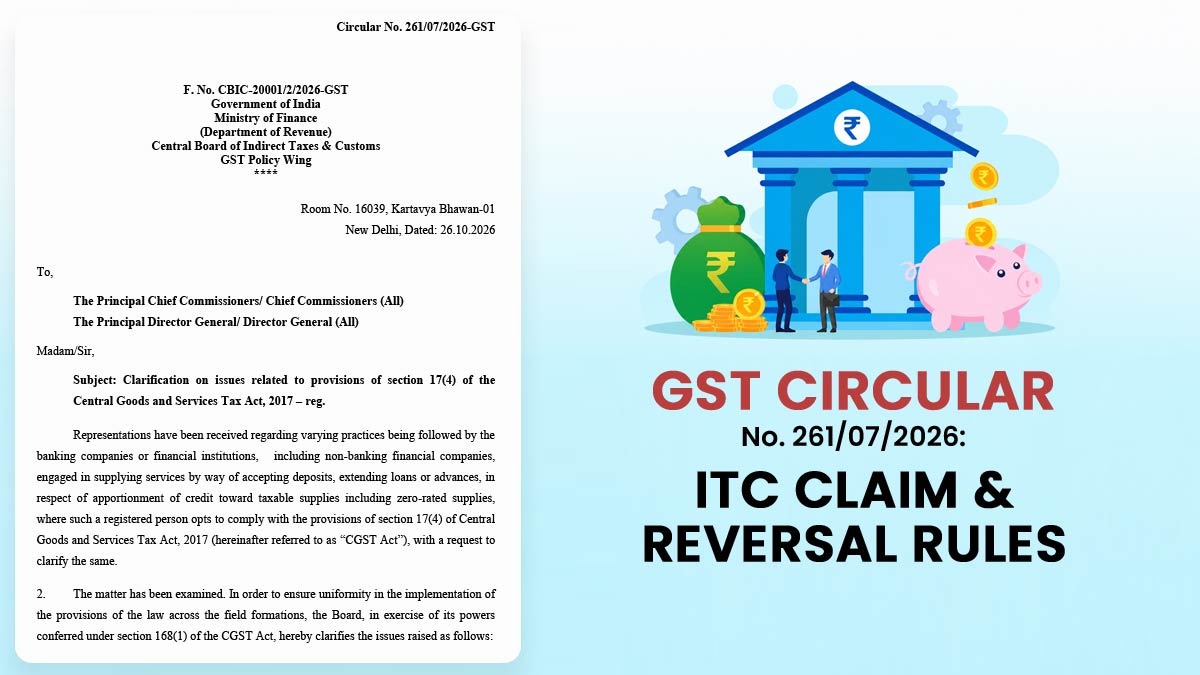


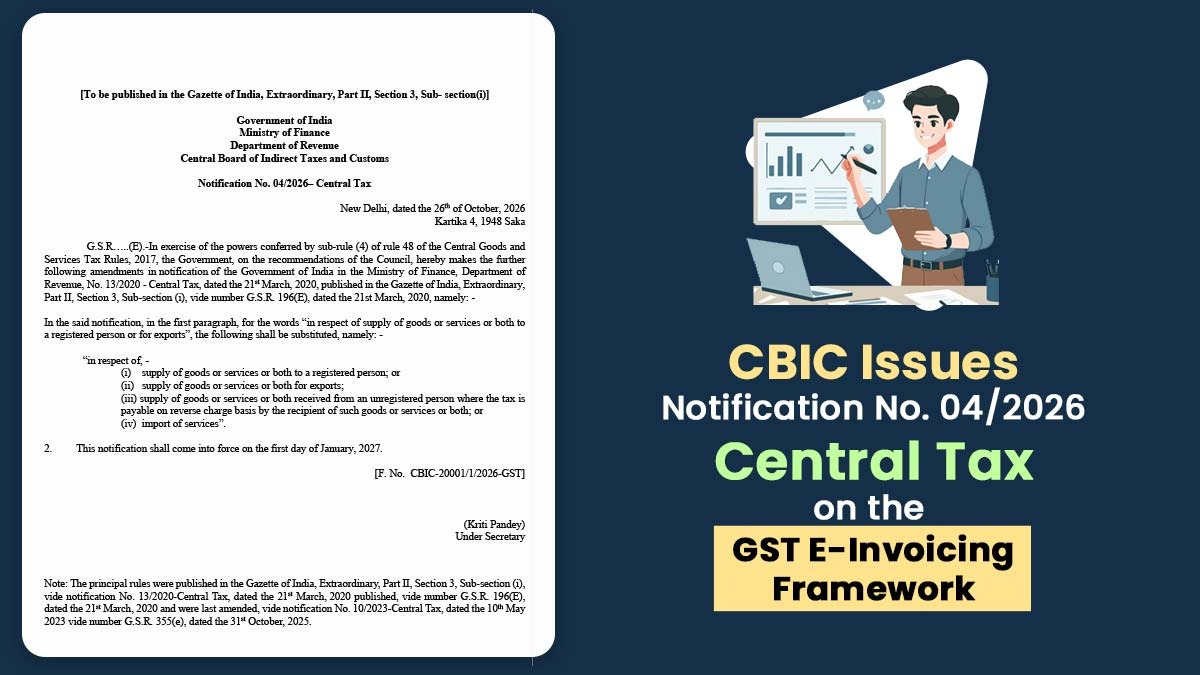
The Central Board of Indirect Taxes and Customs (CBIC) has issued a notification for the expansion of the GST e-invoicing framework, effective January 1, 2027, bringing certain transactions under the Reverse Charge Mechanism (RCM) and imports of services within its scope.
In the amended provisions, electronic invoicing will include supplies obtained from unregistered individuals where the registered recipient is obligated to pay the GST under RCM.
The structure will extend to imports of services, besides existing covered supplies to registered persons and exports.
The revisions change the transaction categories listed under the current e-invoicing notification. Pertinent revisions to the GST electronic invoice schema rolled out other supply-type classifications to accommodate domestic reverse charge transactions and imported services.
The revisions relate to businesses obtaining services from overseas suppliers, making purchases from unregistered persons under RCM, and maintaining automated accounting and GST reporting systems.
Businesses falling within the scope of e-invoicing requirements should review their self-invoicing processes, ERP configurations, and electronic reporting systems before the new provisions come into effect.
The revised requirements will come into effect from January 1, 2027, subject to the existing conditions and exemptions applicable to taxpayers.