

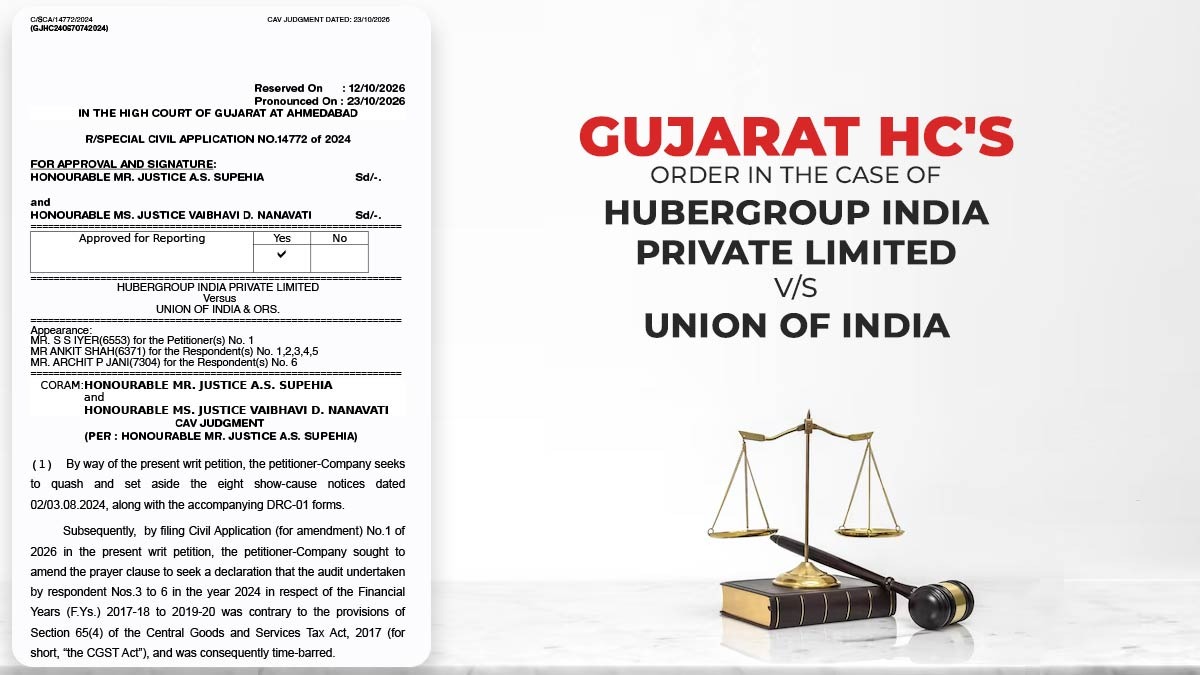
The Gujarat High Court has said that if the documents submitted for a GST audit are incomplete, tax authorities must notify taxpayers within a reasonable timeframe.
“However, we are of the opinion that, where a registered person furnishes documents pursuant to a notice issued under Section 65 of the CGST Act but some documents remain outstanding, the tax authorities are required to inform the registered person of the missing or outstanding documents within a reasonable time, so that the audit can be completed at the earliest,” the court stated.
The Court observed while rejecting HuberGroup India Private Limited’s challenge to the timeliness of a GST audit report. It is stated that the authorities issued three audit notices to the company without specifying which documents were yet to be submitted, which led to the delay.
A bench of Justice A.S. Supehia and Justice Vaibhavi D. Nanavati stated that this failure did not make the audit invalid. The law provides an additional basis for determining when an audit commences: the date on which the audit is actually initiated at the taxpayer’s business premises.
The company obtained its first audit notice on June 27, 2022, covering the period from the financial years 2017-18 to 2019-20.
Read Also: GST | Failure to Intimate Personal Hearing Violates Natural Justice; Gujarat HC Quashes Order
The company filed documents at a hearing on July 12, 2022, and emailed them again on August 9. Another notice was issued by the authorities in November, seeking the same records. In February 2023, HuberGroup filed its purchase register and repeated that it had earlier furnished the other documents.
A third notice was issued in February 2024, which also covered the financial years 2021-22 and 2022-23. In response, the company continued to submit records.
It was claimed by HuberGroup that it had provided the required documents for the earlier years by August 2022, so the audit report issued on August 2, 2024, was time-barred. It contested the eight show cause notices (SCNs) issued on August 2 and 3.
The revenue upheld that some documents were still not submitted and that the audit started at the company’s premises on June 19, 2024.
U/s 65(4) of the CGST Act, an audit should be completed within 3 months of its commencement. The date of commencement of the audit shall be the later of the following two events: the submission of the required documents or the actual commencement of the audit at the taxpayer’s place of business. The court noted that whether all documents had been submitted remains a matter of dispute.
The Court concluded that the audit report had been made within the stipulated 3-month period. It refused to quash the eight SCNs u/s 74 of the CGST Act at this stage, which provides the company a chance to reply to them and contest any resulting measure before the appellate authority u/s 107.
The Court dismissed the writ petition.
| Case Title | HuberGroup India Private Limited vs. Union of India |
| Case No. | NO.14772 of 2024 |
| For the Petitioner | MR. S S Iyer |
| For the Respondent | Mr Ankit Shah and Mr Archit P. Jani |
| Gujarat High Court | Read Order |