

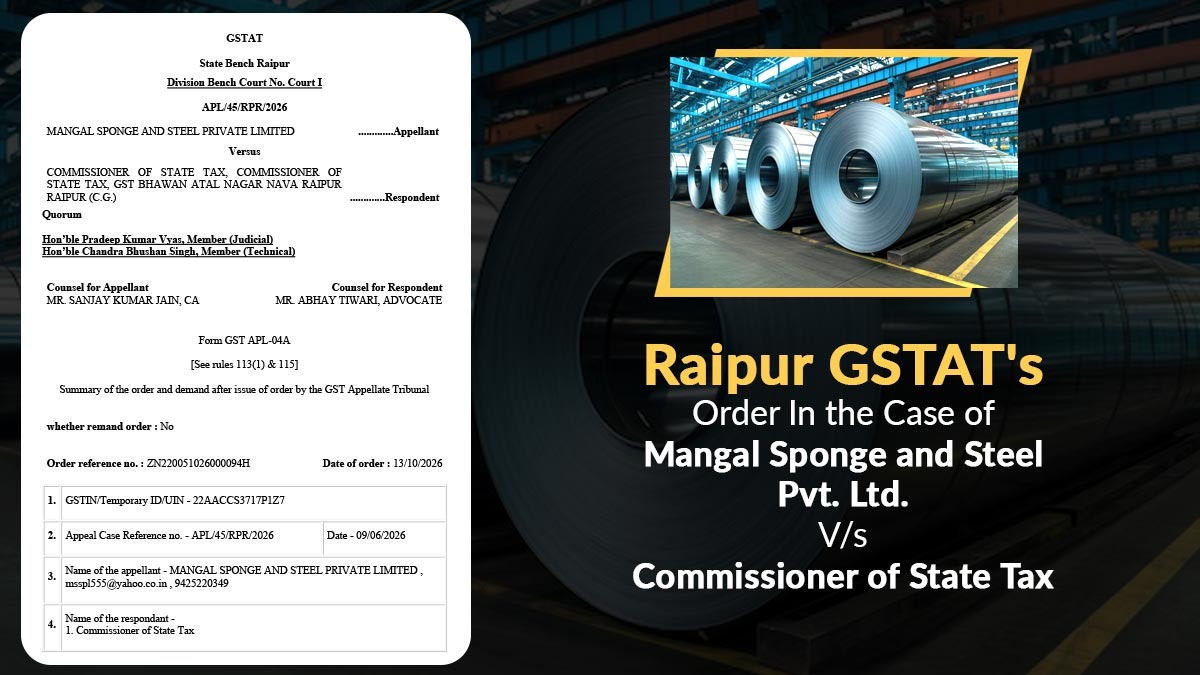
Mangal Sponge and Steel Private Limited transported MS billets whose value is Rs 16,56,675 from Bilha, Bilaspur, to JTL Industries Limited, Raipur, on 12 September 2025. Along with the goods, there were an invoice, a transport bill, and an e-way bill. The State tax officer intercepted the vehicle at Metal Park, Rawabhata on 16 September 2025 and discovered that the GST E-way bill had lapsed on 13 September 2025.
Afterwards, proceedings were initiated under section 129(1)(a) of the GST Act, which resulted in a penalty of Rs 2,98,202 each under the CGST and SGST Acts, aggregating to Rs 5,96,404. The penalty was deposited by the appellant to secure the release of the vehicle.
The appellant contested the order before the appellate authority, which dismissed the appeal on 19 January 2026. The appellant was not satisfied with the decision and approached the GSTAT. The appellant claimed that the e-way bill had lapsed because the vehicle allegedly had faced three breakdowns between 12 and 14 September 2025.
It claimed that the delay was not within its control and that there was no intent to evade tax. The department said that the vehicle was seen transporting goods nearly three days after the e-way bill had lapsed, in breach of Rule 138(10) of the CGST Rules, 2017.
The Tribunal held that, for the purpose of invoking Section 129(1) of the GST Act or imposing a penalty thereunder, it is not mandatory to provide evidence of an intent to evade tax. The Tribunal noted that, unlike the relevant provisions under Section 130, Section 129 does not explicitly stipulate any such condition.
The Tribunal distinguished the judicial precedents cited by the appellant, Assistant Commissioner (ST) Vs Satyam Shivam Papers Private Limited, based on the fact that they involved materially distinct factual situations.
It also held that decisions by the appellate authorities of other states were not binding upon it. Therefore, the Tribunal answered the question of law in favour of the Department, stating that the penalty imposed under Section 129(1)(a) was legally valid.
| Case Title | Mangal Sponge and Steel Pvt. Ltd. Vs Commissioner of State Tax |
| Case No | APL/45/RPR/2026 |
| Counsel for Appellant | Sanjay Kumar Jain |
| Counsel for Respondent | Abhay Tiwari |
| Raipur GSTAT | Read Order |