

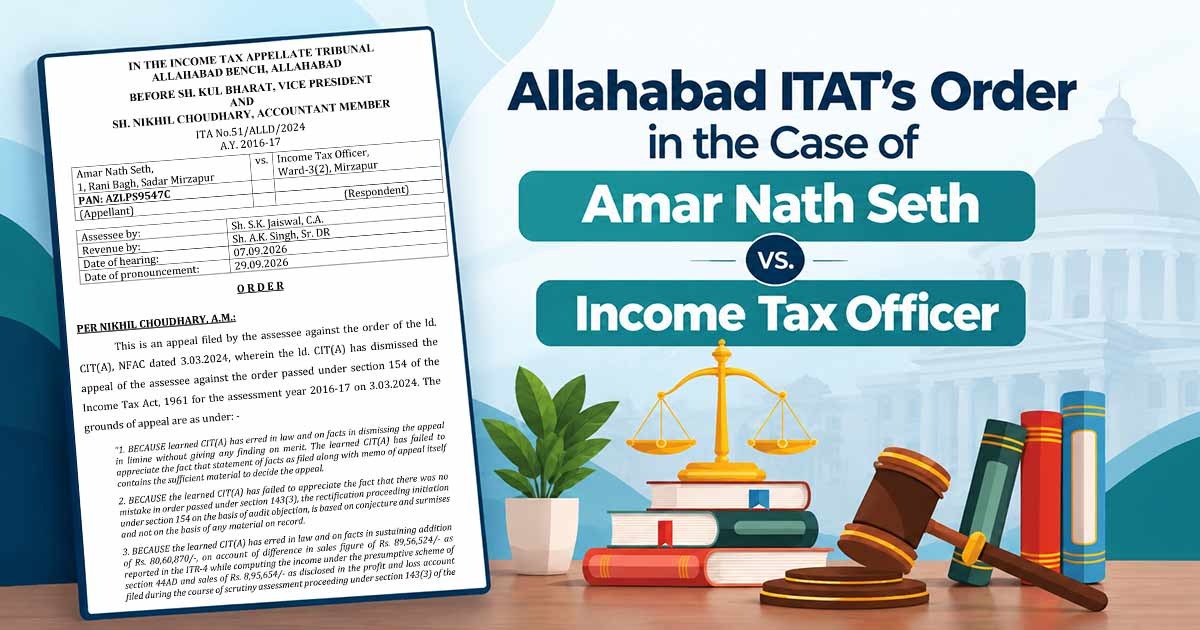
The Allahabad Bench of the Income Tax Appellate Tribunal (ITAT) removed the Rs 80.60 lakh addition emerging via a one-digit error in the sales amount post determination of the correct sales figure, which had been analysed and checked by the assessing officer during the original scrutiny assessment.
The taxpayer, Amar Nath Seth, was in the business of repairing mobile sets and selling animal fodder. U/s 44AD, he reported business income on gross sales of Rs 8,95,654. At the time of ITR filing, the return preparer made a clerical error and entered sales of Rs 89,56,524 instead of Rs. 8,95,654.
The taxpayer, during scrutiny proceedings, has submitted his trading account, profit and loss account, balance sheet, and VAT returns.
The counsel for the taxpayer claimed that the AO got to know about the error in the original assessment and, after checking the VAT return, the Assessing Officer (AO) considered Rs. 8,95,654 as the actual sales figure.
After an objection from a Revenue Audit Party regarding the difference between the ITR and financial statements, the AO invoked Section 154 and added Rs. 80,60,870. The addition has been validated by the CIT(A) after the taxpayer’s failure to file written submissions despite hearing notices.
Before the ITAT, the taxpayer’s counsel argued that Section 154 could not be invoked to alter a view that had been consciously adopted after examination.
The discrepancy was merely a typographical error; the actual sales could be verified from the VAT return, and reopening the matter amounted to a mere change of opinion.
Counsel for the Revenue argued that since the Commissioner of Income Tax (Appeals) had not examined the matter on its merits, the case should be remanded to the CIT(A) for a factual and legal determination, rather than being decided directly by the Tribunal.
A two-member bench, Kul Bharat (Vice President) and Nikhil Chaudhary (Accountant Member), said that the Assessing Officer (AO) had reviewed the discrepancy in sales based on the VAT return and had accepted that it was due to a typographical error.
The Tribunal stated that
“That being the case, the same could not have been held to be as a mistake apparent from the record without pointing out the facts of what the mistake was.”
Read Also: Mumbai ITAT: Assessing Officer Must Examine Source of Funds Despite ITR Technical Errors
The Tribunal also observed that since no error was found in the original assessment, taking action solely based on an audit objection amounted to ‘borrowed satisfaction’. It set aside the rectification made under Section 154, deleted the addition of ₹80,60,870, and allowed the taxpayer’s appeal.
| Case Title | Amar Nath Seth vs. Income Tax Officer |
| Case No. | ITA No.51/ALLD/2024 A.Y. 2016-17 |
| Assessee by | Sh. S.K. Jaiswal |
| Revenue by | Sh. A.K. Singh |
| Allahabad ITAT | Read Order |