

The Income Tax Appellate Tribunal (ITAT), Mumbai, has mentioned that only because of the claim rejection of the taxpayer, a conclusion of concealed facts or false explanation is not drawn.
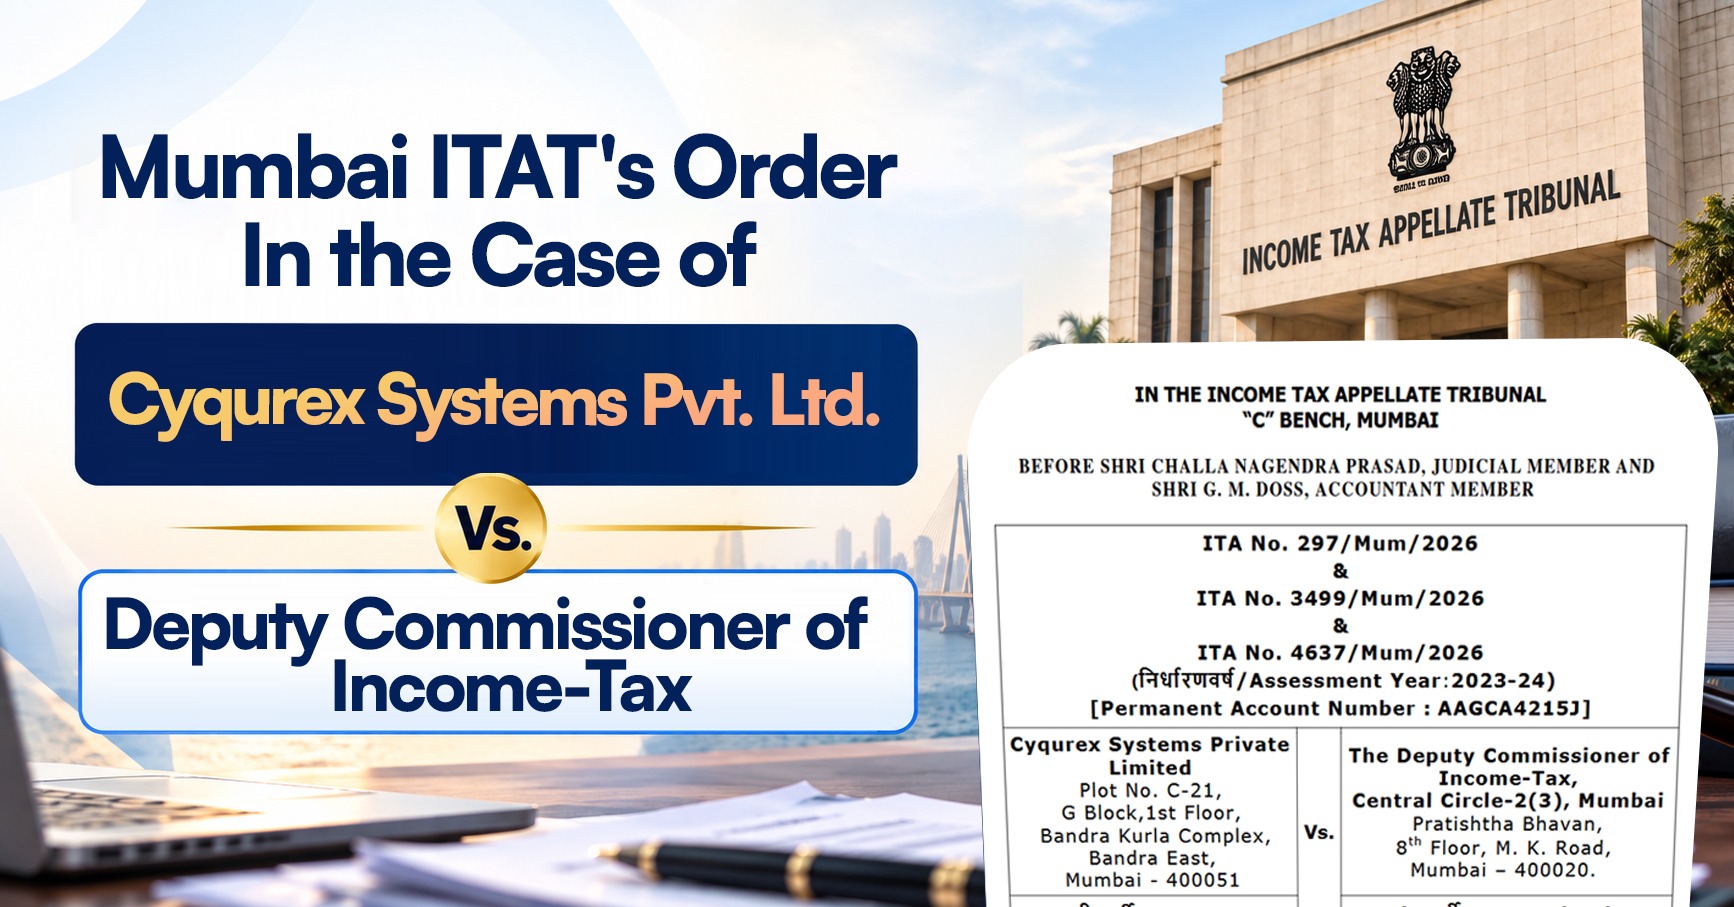
While removing a penalty of Rs 1.23 crore imposed on Cyqurex Systems Pvt. Ltd. under section 270A of the Income Tax Act, the Tribunal made an observation. The penalty was derived from the company’s claim of Rs 7.41 crore as revenue expenditure on software development.
A bench including Judicial Member Challa Nagendra Prasad and Accountant Member G. M. Doss said that:
“The fact that the claim of the assessee was not accepted in the assessment proceedings does not, by itself, establish that the assessee had furnished any false particulars or that the explanation offered by it was not bona fide.”
The bench stated that the question of whether software development expense must be considered as capital or revenue expenditure needs analysis of the facts and applicable legal norms.
For the AY 2023-24, Cyqurex Systems, which develops cyber-security and software solutions, had claimed Rs 7.41 crore as revenue expenditure. The claim had been denied by the assessing officer, and the amount was considered a capital loss.
This expenditure included ₹5.88 crore for the impairment of the internally developed ‘Saife IP asset’ and ₹1.52 crore for the development of the ‘Blackbox’ and ‘Command Control Operating Platform’. The latter had been reflected as ‘Capital Work-in-Progress’.
The company had revealed the expenditure and its accounting treatment in Notes 42 and 43 of its audited financial statements.
Afterwards, the assessing officer levied a Rs 1.23 crore penalty for under-reporting of income. The penalty was upheld by the Commissioner of Income Tax (Appeals).
Before the Tribunal, the company claimed that it had made the claim in bona fide and reported all necessary facts. It contended that the dispute concerned the legal treatment of the expenditure, rather than whether the actual facts had been reported.
Section 270A is concerned with the penalty where the income is under-reported. However, Section 270A(6)(a) does not include an amount in under-reported income where the taxpayer has provided a bona fide explanation and has reported all material facts required to support it.
Also Read: ITAT Grants Relief to Senior Citizen Who Mistakenly Paid Rs. 9.91 Lakh Tax on Tax-Free Bond Interest
The Tribunal found no evidence indicating that the expenses were fictitious or inflated. Furthermore, there was no finding that the company had concealed receipts or assets or provided incorrect information.
The Bench observed that details regarding the expenditure and its accounting treatment were disclosed in the financial statements. The Assessing Officer merely adopted a different legal view, treating the expenditure as capital rather than revenue.
The Tribunal placed reliance on the Bombay High Court’s decision in the G.M. Modular (P.) Ltd. case. It stated that the protection u/s 270A(6)(a) applies where the facts have been disclosed and a bona fide claim has been made regarding a contentious issue.
Therefore, the tribunal removes the Rs 1,23,71,443 penalty imposed on Cyqurex Systems.
| Case Title | Cyqurex Systems Pvt. Ltd. Vs. Deputy Commissioner of Income-Tax |
| Case No. | ITA No. 297, 3499 and 4637/Mum/2026 |
| For Petitioner | Shri Ruturaj H. Gurjar |
| For Respondent | Shri Pankaj Deshmukh |
| Mumbai ITAT | Read Order |