

The Delhi High Court has held that proceedings emerging from a GST audit are different from the adjudicatory proceedings initiated u/s of the Central Goods and Services Tax (CGST) Act, 2017.
The Division Bench of Justices Anil Kshetarpal and Bharat Parashar refused to interfere with an SCN issued to a pharmaceutical distributor under section 74, noting that the taxpayer could raise all its objections before the competent adjudicating authority.
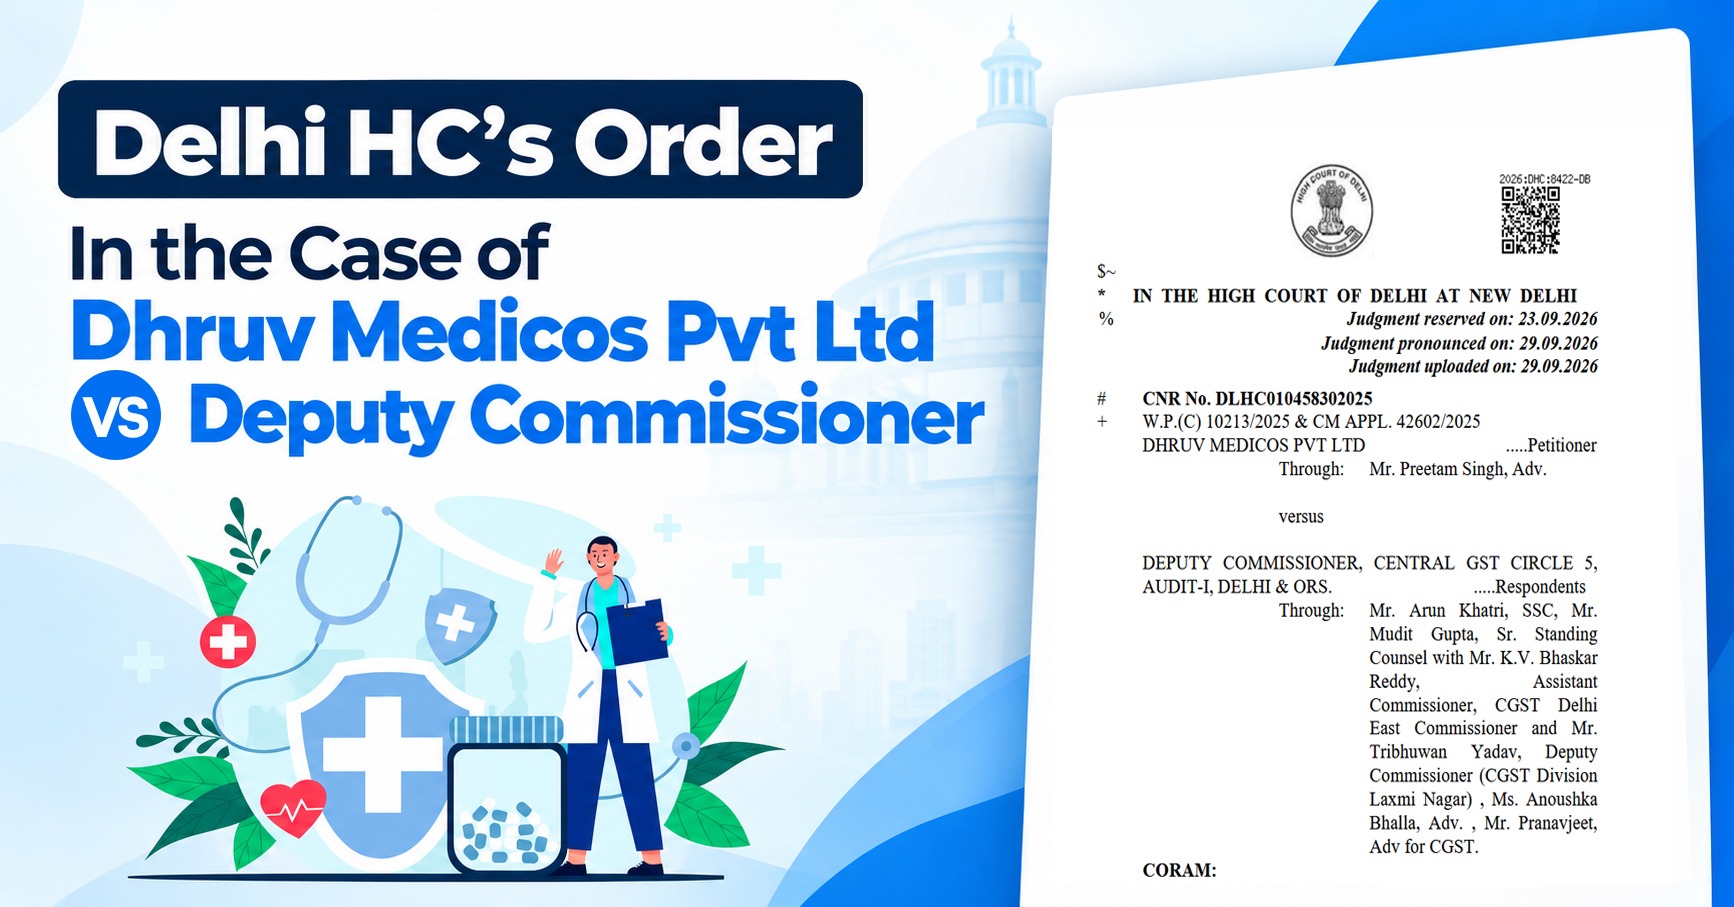
The Court was dealing with a petition of Dhruv Medicos Pvt Ltd contesting an audit report dated April 29, 2025, and a demand-cum-show cause notice dated June 27, 2025.
The company also challenged the utilisation of the amount of ₹40,10,153 deposited via Form GST DRC-03 during the audit. The company alleged that this payment was made under pressure from the audit team.
The reply to the audit objections had been improperly regarded before finalisation of the audit, the applicant claimed. Reliance was placed on Rule 101(4) of the CGST Rules, which requires the proper officer to finalise the audit findings after considering the response provided by the registered person.
The Court observed that the audit proceedings had earlier concluded in the audit report and then the authorities had issued Form GST DRC-01A followed by the Section 74 SCN.
“Thus, the statutory adjudicatory proceedings contemplated under the CGST Act have already been set in motion,” the Court stated.
The Court drew a difference between the audit process and the subsequent adjudication.
“The distinction between an audit proceeding and the subsequent adjudicatory proceeding is material…The Audit Report constitutes the outcome of the audit process. However, once proceedings under Section 74 of the CGST Act have been initiated by issuance of a show cause notice, the Petitioner has an opportunity to place before the adjudicating authority all objections which it seeks to raise against the proposed demand,” it stated.
The Court observed that the objections of the applicant were not confined to the alleged non-consideration of its audit response. These included issues such as time limits, the calculation of proposed liability, jurisdiction, the audit methodology, and the settlement of the ₹40,10,153 payment.
Regarding the contention that action was initiated based on the petitioner’s detailed audit response with the mere remark “not satisfactory,” the Court observed that, at this stage, it cannot be said that the audit officials completely ignored the response.
Also Read: Allahabad HC: GST Section 74 Requires Fraud Proof, Orders Refund with 4% Interest
“Whether the manner in which the reply has been dealt with satisfies the statutory requirement, and whether the objections raised by the Petitioner warrant acceptance, rejection or partial acceptance, are matters which can be examined by the competent Adjudicating Authority,” it stated.
The court allowed the applicant to object before the adjudicating authority along with those relevant to the audit procedure.
| Case Title | Dhruv Medicos Pvt Ltd Vs Deputy Commissioner |
| Case No. | W.P.(C) 10213/2025 |
| For Petitioner | Mr Preetam Singh |
| For the Respondent | Mr Arun Khatri, Mr Mudit Gupta, Mr K.V. Bhaskar Reddy, Mr Tribhuwan Yadav, Ms Anoushka Bhalla, Mr Pranavjeet |
| Delhi High Court | Read Order |