

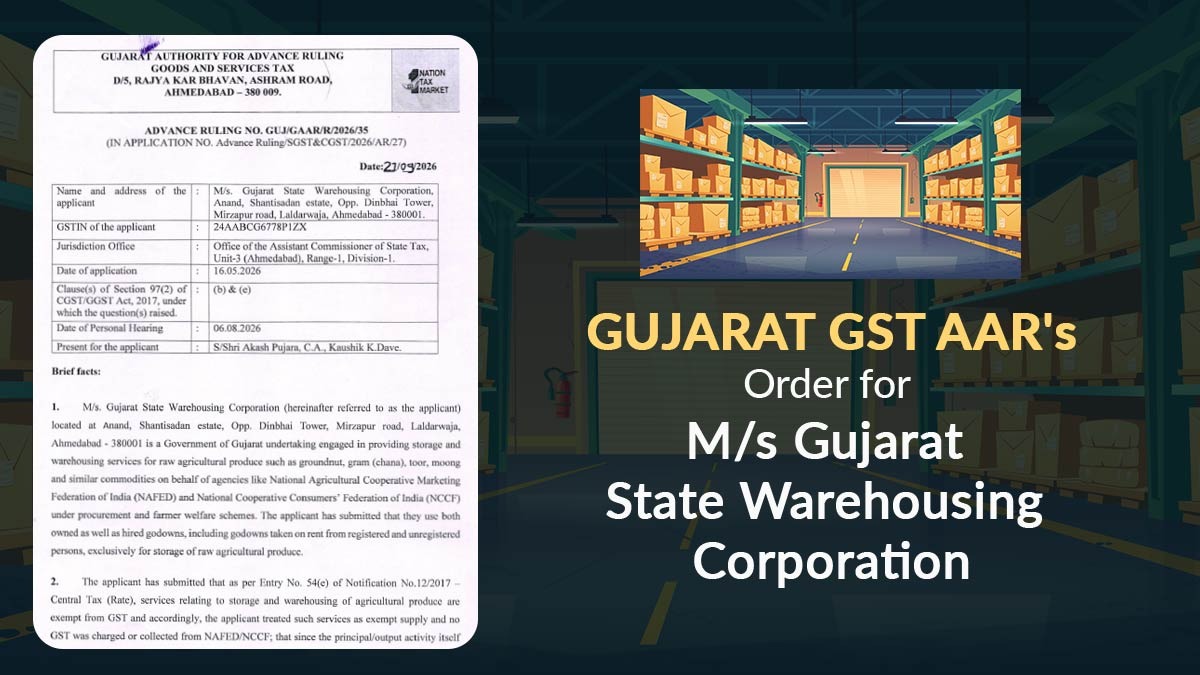
The Gujarat Authority for Advance Ruling (AAR) said that under GST, rent paid to unregistered persons for hiring godowns is subject to tax under reverse charge, even if the godowns are used only to provide exempt storage and warehousing services for agricultural produce.
A Bench of SGST Member Sushma Vora and CGST Member Vishal Malani disposed of the application of the Gujarat State Warehousing Corporation, citing that the hiring of godowns and the warehousing services are separate supplies. The authority said that-
“Regardless of whether the godowns, after being hired on payment of rent from registered/unregistered persons, are used for providing exempt warehousing services in relation to agricultural produce for a consideration, the following constitute two separate services and must be examined independently with reference to the notifications applicable to each: (i) hiring of godowns on payment of rent from registered/unregistered persons; and (ii) providing storage and warehousing services for raw agricultural produce in the applicant’s own godowns as well as in hired godowns, for a consideration. These two services cannot be read in tandem and must be dealt with separately.”
The corporation furnishes storage and warehousing services for agricultural produce, along with groundnut, gram, toor and moong. It uses godowns of its own as well as hired ones and claimed that as the warehousing services furnished from the hired godowns were exempt, the rent paid for such premises must not fall under the GST or be subject to GST under reverse charge.
It placed reliance on Entry 54(e) of Notification No. 12/2017-Central Tax (Rate), which exempts services concerned with the loading, unloading, packing, storage or warehousing of agricultural produce.
The claim has been denied by the authority, and it was discovered that hiring godowns against the rent payment comprises a supply of service under the CGST Act, independently of the warehousing services subsequently provided by the Corporation.
It was observed that the Corporation’s storage and warehousing services for agricultural produce, whether provided through its own warehouses or rented ones, fall within the scope of the exemption under Entry 54(e). However, the renting of godowns falls under Heading 9972 (related to real estate services) and attracts an 18% tax in accordance with the applicable notification.
Thereafter, the Bench mentioned that the reverse-charge position was revised under the Notification No. 09/2024-Central Tax (Rate) dated 8 October 2024, which inserted Entry 5AB into the reverse-charge notification w.e.f. 10 October 2024. Entry 5AB covers, subject to specified conditions, the renting of any property other than a residential dwelling by an unregistered person to a registered person.
It cited that “from a plain reading of the above Entry, it is apparently clear that GST at the rate of 18% (9% CGST + 9% SGST) will be payable by the applicant on a reverse charge basis in the cases where they are hiring godowns from unregistered persons w.e.f. 10.10.2024. In view of the discussions in paras supra, we find and hold that the GST at the rate of 18% (9% CGST + 9% SGST) is payable by the applicant under reverse charge basis on the rent paid for the godowns hired from unregistered persons.”
The Authority also denied the Corporation’s argument citing an ‘advance ruling’ (a prior decision) issued by the Tamil Nadu Authority. That ruling pertained to the rent of godowns used for storing paddy and other agricultural produce. The Authority stated that an ‘advance ruling’ applies only to the applicant who sought it and the officer with the relevant jurisdiction; therefore, that ruling could not be applied to the present case.
Subsequently, the AAR stated that GST is applicable on rent paid for hired godowns used for storage and warehousing of raw agricultural produce. If godowns are rented from an unregistered person, the rent will be subject to an 18% tax under the reverse charge mechanism comprising 9% CGST and 9% SGST, effective from October 10, 2024.
| Case Title | M/s Gujarat State Warehousing Corporation |
| Advance Ruling No. | GUJ/GAAR/R/2026/35 |
| GSTIN of Applicant | 24AABCG6778P1ZX |
| Present for the Applicant | S/Shri Akash Pujara, Kaushik K.Dave. |
| Gujarat AAR | Read Order |