

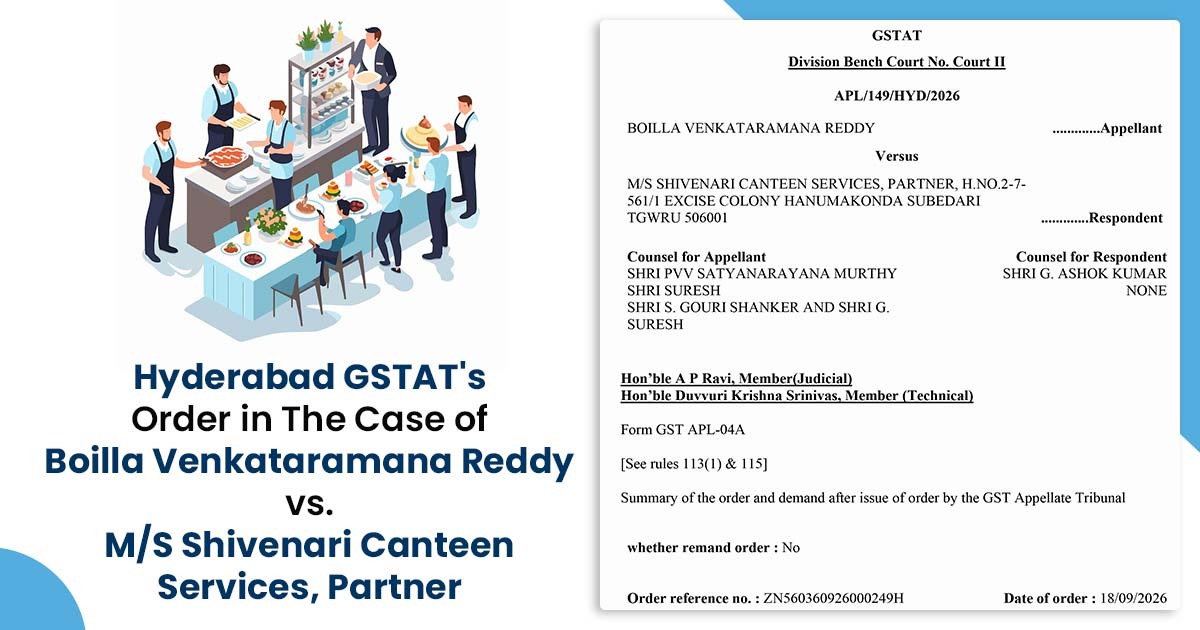
The Hyderabad Bench of the Goods and Services Tax Appellate Tribunal (GSTAT) has ruled that food provided by an outsourced caterer under a contract with a hospital does not qualify as a ‘composite supply’ of healthcare services, even if the food is consumed by patients who are admitted to the hospital.
The department challenged an order issued by the First Appellate Authority. That order had classified the food served to patients admitted to MGM Hospital as part of a composite healthcare supply and had set aside the demand for the associated tax, interest, and penalty.
The Revenue contended that CBIC Circular No. 32/06/2018-GST pertained to healthcare services provided by clinical establishments or healthcare providers. From the department’s perspective, the respondent was merely an outsourced caterer supplying food to MGM Hospital and did not itself provide healthcare services.
They mentioned that the supply was subject to tax as restaurant service and asked to restore the demand of Rs 23,04,026 for January 2018 to November 2021.
The counsel of the respondent said that under an agreement, the food was supplied in the hospital to inpatients on the advice of doctors or nutritionists, which formed part of healthcare services. It placed reliance on the Board circular and communications from the Principal Accountant General and MGM Hospital.
Read Also: GST Impact on the Healthcare Industry in India
The Bench, A P Ravi ( Judicial Member) and Duvvuri Krishna Srinivas (Technical Member), said that, “Apply the above to the case on hand, it would be clear that in the hands of the Respondent there is only one supply viz., supply of food.”
It said that “Apart from supply of food, there is no other supply in the hands of the Respondent and as such the provisions of Section 2(30) of the Act cannot be applied to the instant case.”
The Tribunal said that the FAA had made a mistake in treating the supply as a composite supply.
On Section 74, it stated that, “Except for the gross error in understanding the law and the clarification provided by the Board, we don’t find any reason for invoking the provisions of Section 74 of the Act.”
Read Also: Supreme Court: Section 74 Cannot Be Invoked Without Proof of Fraud or Fake ITC
A direction was issued to accept the demand under Section 73 while simultaneously granting the benefit of lower-tax valuation under Rule 35. With these modifications, the Department’s appeal was allowed.
| Case Title | Boilla Venkataramana Reddy vs M/S Shivenari Canteen Services, Partner |
| Case No. | APL/149/HYD/2026 |
| Hyderabad GSTAT | Read Order |