

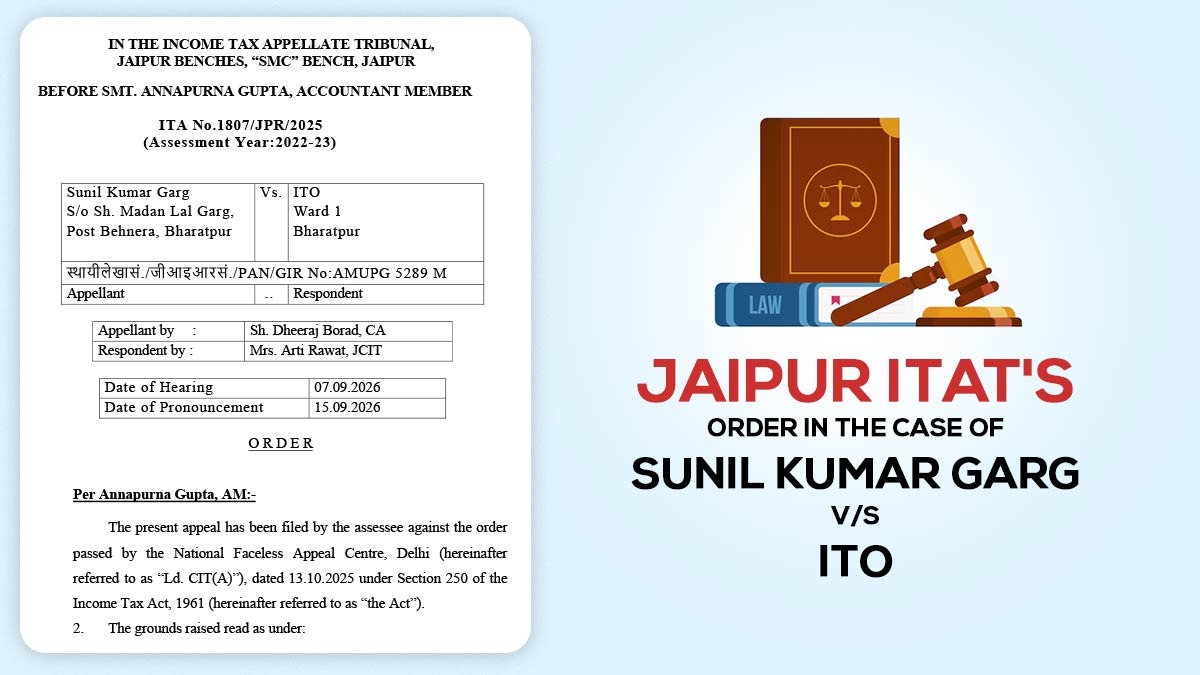
The Jaipur Bench of the Income Tax Appellate Tribunal (ITAT) has removed Rs 31.40 lakh addition u/s 69A, determining that the source of cash deposits had been supported by bank records showing gifts received from the taxpayer’s parents, cash withdrawals, and subsequent deposits into a post office savings account.
Sunil Kumar Garg (the taxpayer) had deposited a total of ₹31.40 lakh into a Post Office savings account opened jointly with his wife, Vandana Garg. The taxpayer stated that these funds primarily came from gifts received from his parents.
They showed their parents’ bank statements, which revealed the amounts given to them. They also presented their own bank accounts, detailing the receipt of funds and the subsequent cash withdrawals.
The taxpayer cited the proceeds from the closure of four term deposits totaling approximately ₹9.03 lakh, out of which ₹4.50 lakh was withdrawn in cash. He also stated that ₹30,000 came from old cash savings.
Read Also: Income Tax Liabilities on Marriage Gift & for Divorced Couples
The account of the post office is shown to establish that the withdrawn cash was subsequently deposited there.
The counsel of the taxpayer has mentioned that the flow of money had been backed by documentary proof. He stated that the Assessing Officer had rejected the explanation primarily because withdrawing cash from one account and depositing it into another appeared illogical, given that the amount could have been transferred directly through banking channels.
The counsel’s revenue placed reliance on the findings of the Assessing Officer and the CIT(A).
The single-member bench comprising Annapurna Gupta (Accountant Member) has said that the taxpayer had reported the receipt of gifts via banking channels, withdrawal of the same amounts in cash, and their following deposit into the post office account.
Recommended: ITAT: Affidavits by Family Members for Gifts Considered Genuine
The tribunal stated that, “The facts pointed out by the Ld. Counsel for the assessee explaining the entire trail of money received by the assessee from his parents to one of his bank accounts from which he withdrew cash and deposited in his post office savings bank account has not been disputed by the Revenue.”
It stated that, “I do not find any merit in the order of the Authorities below rejecting the assessee’s explanation on the mere ground of unreasonableness.” The tribunal said that the revenue did not claim that the cash withdrawn had been utlised in other things. It removed the Rs 31.40 lakh addition, and the taxpayer’s appeal was allowed.
| Case Title | Sunil Kumar Garg vs ITO |
| Case No. | ITA No.1807/JPR/2025 |
| For Petitioner | Sh. Dheeraj Borad, CA |
| For Respondent | Mrs Arti Rawat, JCIT |
| ITAT Jaipur | Read Order |