

Calcutta HC Grants GST ITC Relief, Quashes ₹1.18 Crore Demand Over GSTR-3B Filing Delay
The Calcutta High Court has set aside a 1.18 crore GST demand and granted retrospective ITC relief for the late filing of GSTR-3B.
The applicant, Manash Ghosh, contested the legality and sustainability of the adjudication order dated 19 April 2024, passed u/s 73 of the Central Goods and Services Tax Act, 2017 (CGST Act) for the FY 2018–2019.
The applicant stated that the adjudication order refusing the benefit of ITC was unsustainable in light of the subsequent amendment to Section 16 of the CGST Act by insertion of sub-section (5) through the Finance (No. 2) Act, 2024. The amendment specified regularised the ITC claim for the financial years 2017–2018 to 2020–2021, given that the related returns were provided on or before 30 November 2021.
The applicant mentioned that Section 16(5) of the CGST Act, inserted w.e.f. 1 July 2017, is applicable to the applicant. The applicant had submitted the GSTR-3B returns for April 2018 to March 2019 before 30 November 2021, though belatedly. Therefore, the applicant is qualified for the benefit of the amendment, and the ITC refusal is not legal.
Even after the amendment, the respondent passed an order on April 19, 2024, demanding ₹1,18,35,089/- for the financial year 2018–19; therefore, it was argued that this demand is unsustainable and ought to be quashed.
The court in Hiranmoy Dutta v. State of West Bengal said that where ITC was disallowed only because the applicant had submitted GSTR-3B returns beyond the deadline, the insertion of Section 16(5) of the CGST Act regularised these returns if filed within the extended cut-off date. Therefore, the applicant must have the benefit of the amendment.
The respondent authorities’ counsel said that the case of the applicant does not fall under the inserted clause, which has been rolled out w.e.f. 1st July, 2017 and the order has earlier been passed via the pertinent authority and that Section 16(5) of the CGST Act cannot be invoked to reopen a concluded assessment. The amendment benefit is conditional upon the return filing by 30th November, 2011, it argued.
Justice Smita Das De said that “This Court finds that by virtue of the inserted clause, as amended in Section 16, the petitioner cannot be denied the benefit of such amendment. The amendment is curative and retrospective from 01.07.2017. Once returns are filed by 30.11.21, input tax credit for April, 2018 to March, 2019 is regularized.”
The Court observed that the order-in-original should be re-adjudicated by the Joint Commissioner u/s 16(5) of the CGST Act, after checking the filing date of the GSTR-3B returns, within 6 weeks. The Court also directed the respondent officials not to take any punitive or harsh measures against the petitioner until the rehearing is concluded.
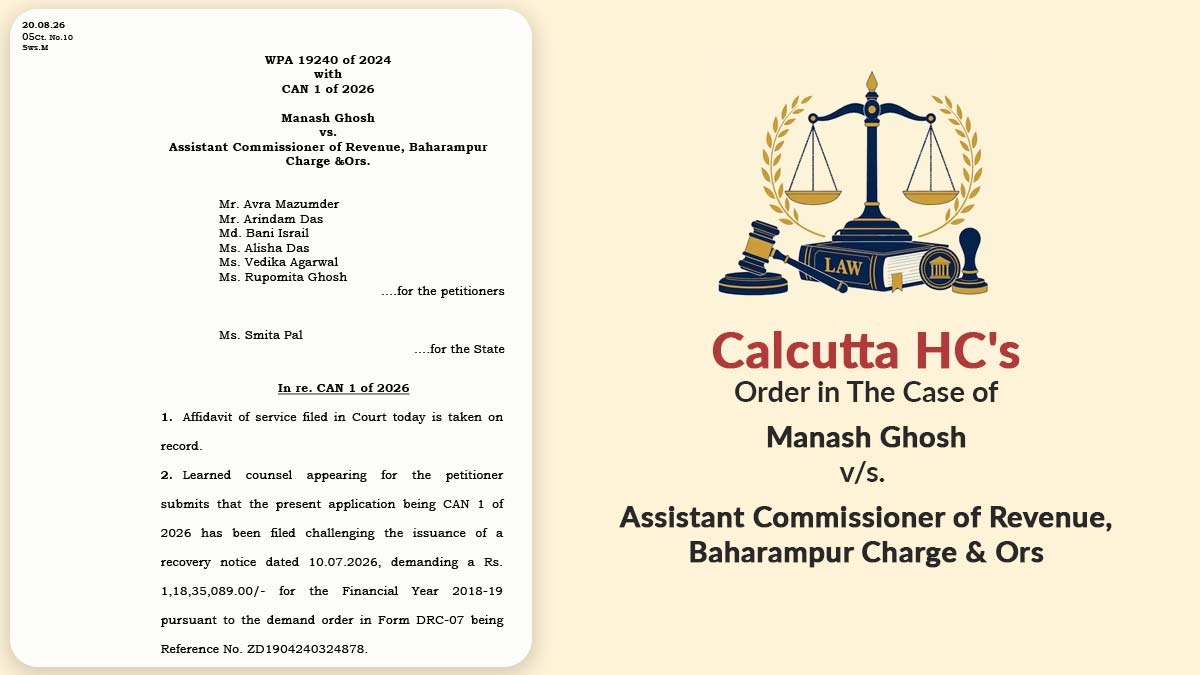
| Case Title | Manash Ghosh vs. Assistant Commissioner of Revenue, Baharampur Charge & Ors |
| Case No. | WPA 19240 of 2024 with CAN 1 of 2026 |
| For Petitioner | Mr. Avra Mazumder Mr. Arindam Das Md. Bani Israil Ms. Alisha Das Ms. Vedika Agarwal Ms. Rupomita Ghosh |
| For Respondent | Ms. Smita Pal |
| Calcutta High Court | Read Order |