

The Telangana High Court has restored the GST registration of a marble and granite trader. The court held that cancelling the registration due to a dispute over the rented business premises was unjustified, especially given that civil litigation between the parties is still pending.
A bench comprising Acting Chief Justice P. Sam Koshy and Justice Suddala Chalapathi Rao observed that the trader was in possession of the premises as a tenant, and no clear stay order against him had been presented before the court.
The Bench further stated that the applicant cannot be evicted without a decree from a competent civil court. It preserved the rights of the tax department to take measures in accordance with the law, subject to the final result of the pending civil proceedings. The applicant was involved in trading marble and granite from rented premises in Hyderabad.
As per the facts recorded in the judgment, the original property owner executed a rental agreement in favour of the applicant dated May 12, 2017. The firm obtained GST registration, which came into force on July 1, 2017. Thereafter, the original owner transferred the property to her son, Dr B. Venkateshwar Rao, via a registered gift deed on March 12, 2021.
Subsequently, disputes arose between the parties. The petitioner’s proprietor filed O.S. No. 5317 of 2025 in the City Civil Court, Hyderabad, before the V Junior Civil Judge, seeking a perpetual injunction against the original owner and his son.
Subsequently, the son filed O.S. Nos. 751 and 968 (of the year 2026), seeking a perpetual injunction and the eviction of the petitioner from the property, respectively.
He also filed a complaint with the tax authorities, alleging that the applicant has received a GST registration for his property without his explicit permission or consent.
The authorities, acting on the complaint, issued an SCN. however the applicant filled a response, the Deputy State Tax Officer issued an order on September 30, 2026, in Form GST REG-19, cancelling its registration based on fraud, wilful misstatement or suppression of facts. The trader contested the order before the High Court.
The applicant’s counsel claimed that the issue at hand was addressed by a common order from a coordinate bench dated September 2, 2025, regarding W.P. Nos. 10470 and 10834 of 2020.
This previous ruling dealt with competing claims over property and businesses, while a partition suit was pending before a civil court.
The coordinate bench had stated that GST authorities should not intervene in civil disputes or conflicting claims that involve the authenticity and validity of documents such as wills, as well as matters about succession.
It had stated that “the appropriate jurisdiction in such matters lies with the Civil Court.”
In those proceedings, the court set aside the interim suspension of the competing GST registrations and ruled that, once the civil court has determined the rights of the parties, the authorities may take appropriate action in accordance with the law.
In the current case, the Assistant Government Pleader for State Tax did not contest the applicant’s claim that the issue was already addressed in a previous decision.
The Division Bench observed that the applicant was in possession of the premises as a tenant. It also recorded that the lawsuits for eviction and perpetual injunction between the parties were still pending in the competent civil court. Importantly, there were no documented positive restraint orders against the applicant.
Under these circumstances, the court held that the cancellation of the GST registration based on the stated grounds of fraud, willful misstatement, or suppression of facts cannot be sustained.
The Bench mentioned that, “the petitioner cannot be dispossessed from the subject premises without a decree from the Civil Court.”
Thus, it concluded that the cancellation order was obligated to be quashed.
The High Court quashed the cancellation order on September 30, 2026, and explicitly restored the applicant’s GST registration.
The Court said that its decision shall not prevent the respondent authorities from taking measures in accordance with law, subject to the final result and adjudication of the pending civil suits.
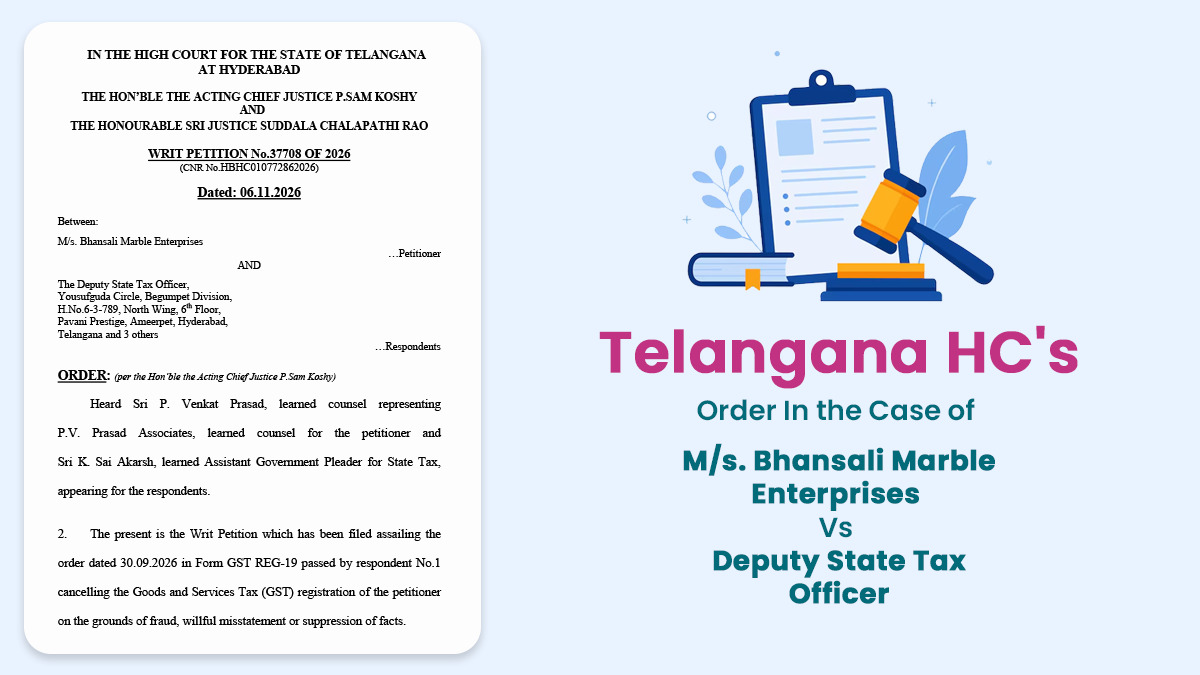
| Case Title | M/s. Bhansali Marble Enterprises Vs Deputy State Tax Officer |
| Case No. | Writ Petition No.37708 of 2026 |
| For Petitioner | Sri P. Venkat Prasad |
| For Respondent | Sri K. Sai Akarsh |
| Telangana High Court | Read Order |