

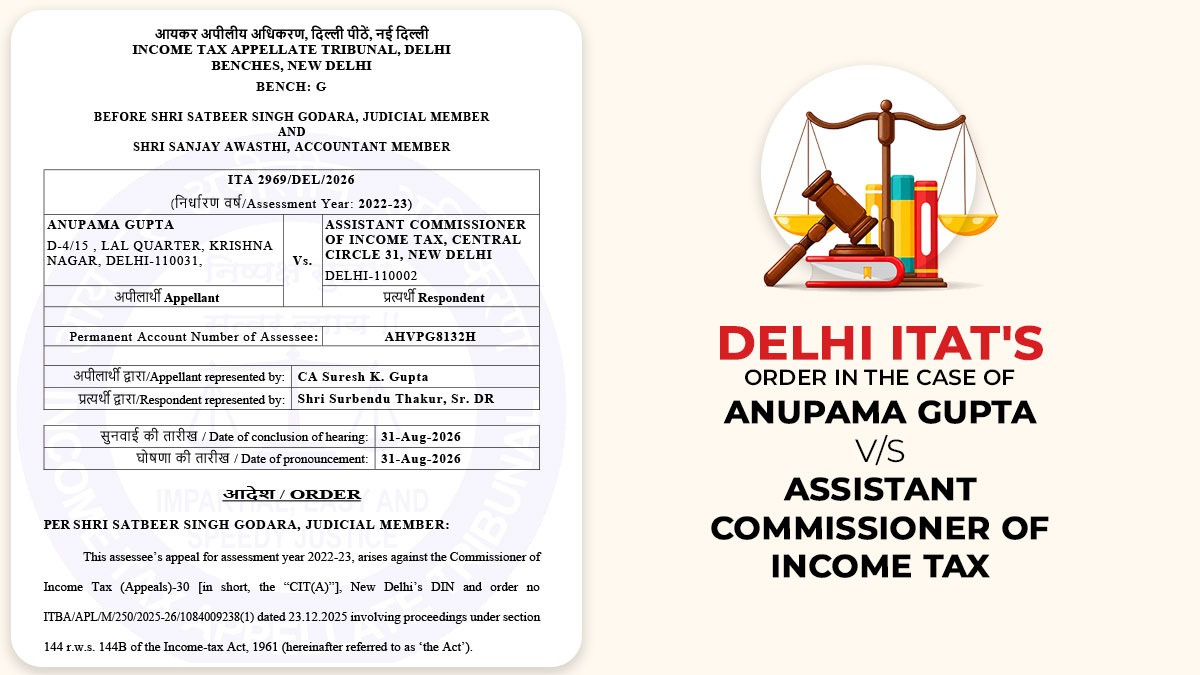
The Income Tax Appellate Tribunal (ITAT), Delhi Bench, has granted partial relief to Anupama Gupta. The Tribunal has reduced the 20% disallowance made by the Assessing Officer (AO) in relation to alleged bogus purchases to 1%.
The taxpayer was involved in the business of trading in finished fabrics and had declared total purchases of Rs 2.54 crore during AY 2022-23.
The AO deemed the purchases, amounting to Rs 50.95 lakh, to be bogus and expressed suspicion that these were ‘accommodation entries’.
Therefore, the AO completed the assessment u/s 144 read with Section 144B of the Income Tax Act, 1961, and disallowed 20% of the total purchases, amounting to Rs 50.95 lakh. Thereafter, the Commissioner of Income Tax (Appeals) [CIT(A)] upheld the addition.
Dissatisfied with this decision, the taxpayer approached the ITAT. During the proceedings, the Tribunal said that the taxpayer was engaged in the fabric business, and the possibility that he might have made purchases from unregistered dealers could not be entirely ruled out.
It was also stated that the lower-level entities had raised no objections to the sales in question. Furthermore, these entities had, in principle, accepted 75% of the purchases.
The Tribunal considered the facts and judicial precedents for fake purchases and stated that, “a lumpsum GP disallowance @ 1% of the assessee’s alleged bogus purchases amounting to Rs. 50,950/- u/s 37 and not u/s 115BBE of the Act, would be just and proper. The assessee’s book entries are hereby rejected to the very extent. Necessary computation shall follow as per law.”
Therefore, instead of invoking Section 115BBE, the ITAT limited the disallowed amount to Rs 50,950 u/s 37 of the Income Tax Act. The Tribunal further directed that the taxpayer’s books of account be rejected to that extent, and partially allowed the appeal.
| Case Title | Anupama Gupta vs. Assistant Commissioner of Income Tax |
| Appellant by | CA Suresh K. Gupta |
| Respondent by | Shri Surbendu Thakur |
| Delhi ITAT | Read Order |