

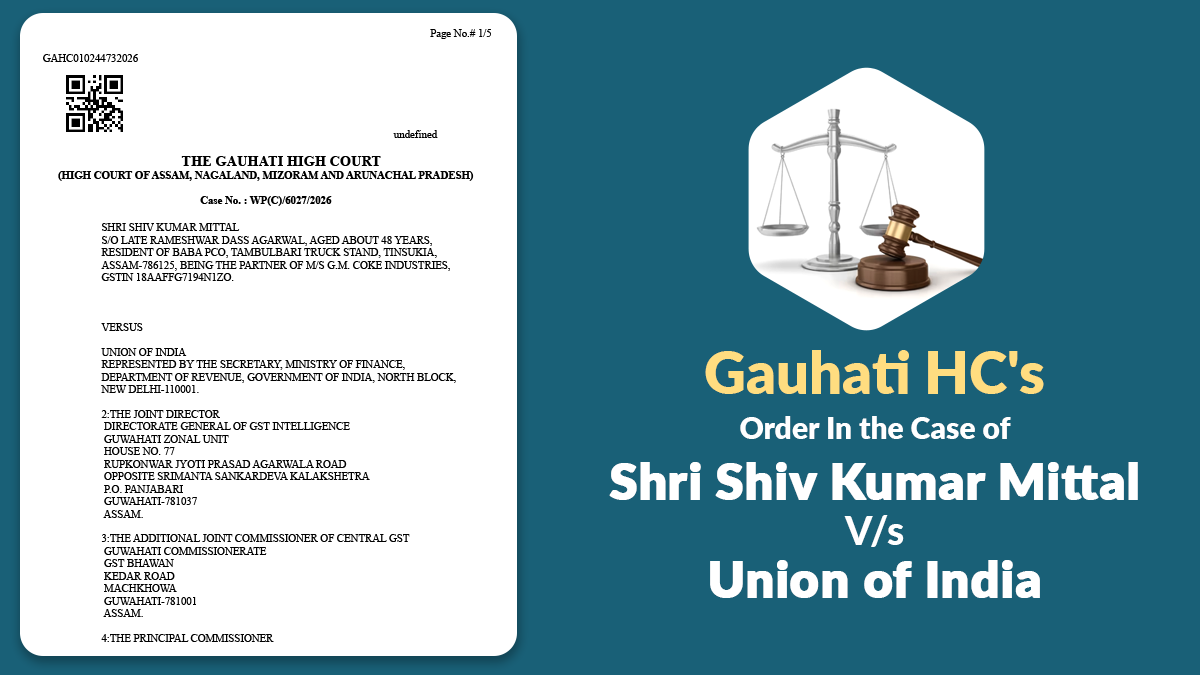
On November 4, the Gauhati High Court passed an interim order on a petition filed by a partner of ‘GM Coke Industries’. Under this order, GST authorities have been restrained from taking any further action based on a ‘show-cause notice’.
This notice pertained to a proposal to impose a penalty u/s 122(1)(A) of the Central Goods and Services Tax (CGST) Act, 2017.
Justice Soumitra Saikia observed that if recovery proceedings for disputed Input Tax Credit (ITC) have already been initiated against a partnership firm in connection with the firm’s allegedly wrongful claim of ITC, then separate penalty proceedings against an individual partner in the same matter may not be necessary. The bench stated:
“the proceedings initiated by the respondents against M/S GM Coke Industries, which appears to be a partnership, further proceedings in respect of one of the partners individually for the benefits purportedly wrongly claimed by the partnership firm towards ITC sought to be recovered and for which proceedings are sought to be initiated including imposition of penalty, separate proceedings against one of the partners for such benefits purportedly stated to be wrongly claimed by the partnership firm does not appear to have been necessary in the view of the Court.”
GM Coke Industries contested an SCN on 30 September 2026, which proposed to levy a penalty on it individually for an allegedly incorrect claim of ITC by the partnership firm, which is in the manufacture of coke.
The department alleged that the firm claimed an Input Tax Credit (ITC) of Rs 16.21 crore based on invoices issued by 17 suppliers and their corresponding GST e-way bills, even though no goods were actually received. The department had already issued a separate ‘show cause notice’ to the firm to recover this allegedly wrongful ITC.
Subsequently, the court initiated separate proceedings against the applicant and proposed the imposition of a penalty u/s 122(1)(a), because he was a partner in the firm.
Appearing on behalf of the applicant, Senior Advocate Dr Ashok Saraf argued that the benefit of the disputed Input Tax Credit (ITC) was availed by the partnership firm, and not by the petitioner in their personal capacity.
He said that since the department has already initiated proceedings against the firm, it cannot be considered appropriate to commence separate penalty proceedings against an individual partner for the same alleged act.
He placed reliance on the ruling of the Supreme Court in Dhanasihgh Prabhu v. Chandrasekar & Ors., stating that the obligation of a partnership firm extends jointly and severally to its partners.
Read Also: GSTAT: GST Portal Technical Errors Cannot Prejudice Taxpayer’s Statutory Right of Appeal
Before making its prima facie observation against initiating separate proceedings, the bench considered the arguments presented and the material on record.
The court issued a notice to the respondents, requiring a response within four weeks, and granted them time to seek instructions and file their affidavits.
The court further directed the authorities not to take any further action pursuant to the impugned ‘show-cause notice‘ until the next date of hearing.
The matter is scheduled for 9 December 2026.
| Case Title | Shri Shiv Kumar Mittal vs. Union of India |
| Case No. | WP(C)/6027/2026 |
| For the Petitioner | Dr Ashok Saraf, Mr A. Kaushik, Mr P. K. Bora, Mr N. N. Dutta, and Mr P. Baruah |
| For the Respondent | Dy. S.G.I. and Mr B. Gogoi |
| Gauhati High Court | Read Order |