

The Gujarat Authority for Advance Ruling has stated that GST is not liable to be paid on amounts recovered via Torrent Pharmaceuticals Ltd. from employees for canteen meals at its Indrad plant, R&D facility, and corporate office.
The AAR stated that the deductions made from employees do not direct to a supply u/s 7 of the CGST Act.
The Authority stated that, “We hold that the deduction made by the applicant from the employees who are availing food in the factory/corporate office would not be considered as a ‘supply’ under the provisions of section 7 of the CGST Act, 2017.”
Read Also: Gujarat GST AAR: ITC on Employer-Provided Canteen Services (Excluding Employee Contribution)
SGST Member Sushma Verma and CGST Member Vishal Malani provided the ruling.
Torrent had asked for the ruling on employee recoveries for canteen facilities at its Indrad plant, R&D facility at Bhat, Ahmedabad, and corporate office at Torrent House, Ahmedabad.
In its Indrad plant and R&D facility, there are more than 250 employees and 100 employees at its corporate office.
For its Indrad plant and R&D facility, Torrent relied on Section 46 of the Factories Act, 1948, which mandates the provision and maintenance of canteen facilities for factories employing more than 250 workers.
For the corporate office, it relied on Section 23 of the Gujarat Shops and Establishments (Regulation of Employment and Conditions of Service) Act, 2019. Under this provision, it is mandatory for an establishment with 100 or more employees to provide and maintain canteen facilities.
Under Torrent’s canteen policy, the cost of meals was shared between the management and its workforce. At the Indrad manufacturing plant and R&D facility, the company provided a 50% subsidy on breakfast, meals, and snacks, deducting the remaining employee share directly from salaries. At the corporate headquarters, the subsidy rate was structured dynamically based on the employee’s pay grade.
The canteen service provider raised invoices on Torrent and levied 5% GST. The company did not make any profit margin from the amounts recovered from employees.
The AAR analysed whether these deductions from employees’ salaries could be accepted as ‘consideration’ for the services provided by Torrent.
It took note of the statutory obligation to provide canteen facilities and also considered the company’s canteen policy and the agreement with the service provider. Regarding the corporate office as well, it found that the canteen was being operated in compliance with the requirements of Section 23.
The AAR has reviewed Section 17(5)(b) of the CGST Act, which disallows Input Tax Credit (ITC) on food and beverages; however, a provision within the section permits ITC when the supply of such food or beverages is obligatory for the employer under the law.
Thus, the authority stated that Torrent could claim ITC on GST levied via the canteen service provider. However, the credit was limited only to the expenses incurred by the company.
Therefore, the AAR ruled that GST was not liable to be paid on the employee recoveries and that Input Tax Credit (ITC) was available only to the extent of the cost incurred by Torrent.
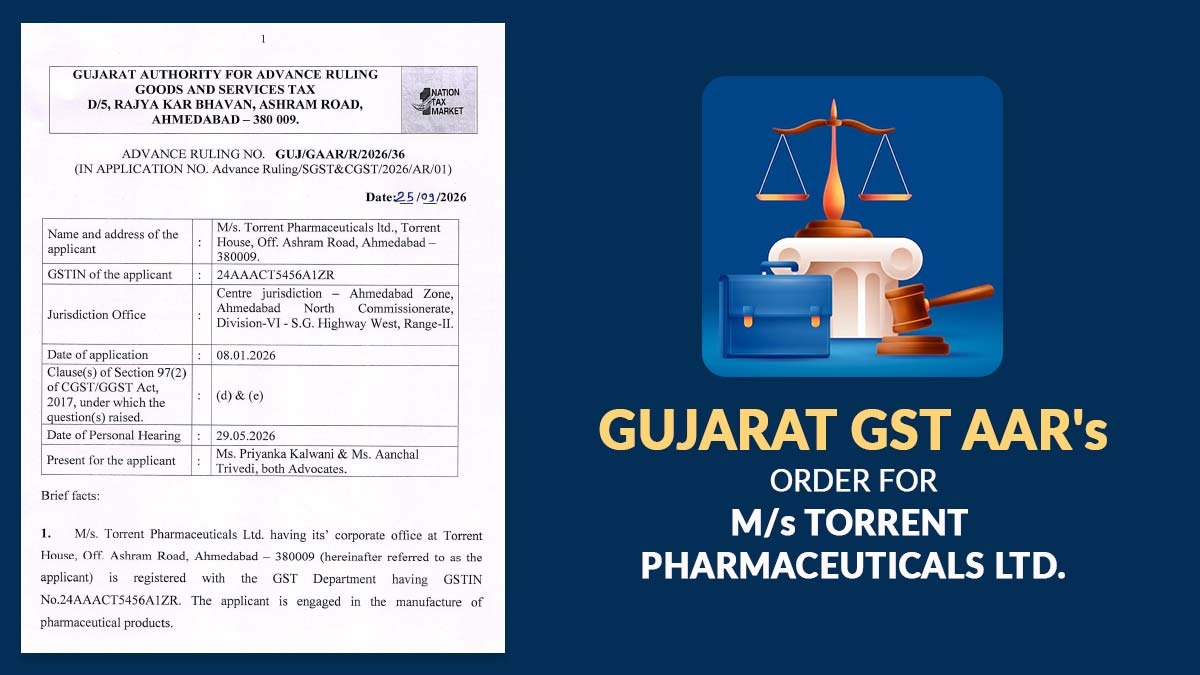
| Case Title | M/s Torrent Pharmaceuticals Ltd. |
| Advance Ruling No. | GUJ/GAAR/R/2026/36 |
| GSTIN | 24AAACT5456A1ZR |
| For The Applicant | Ms Priyanka Kalwani, Ms Aanchal Trivedi |
| Gujarat AAR | Read Order |