

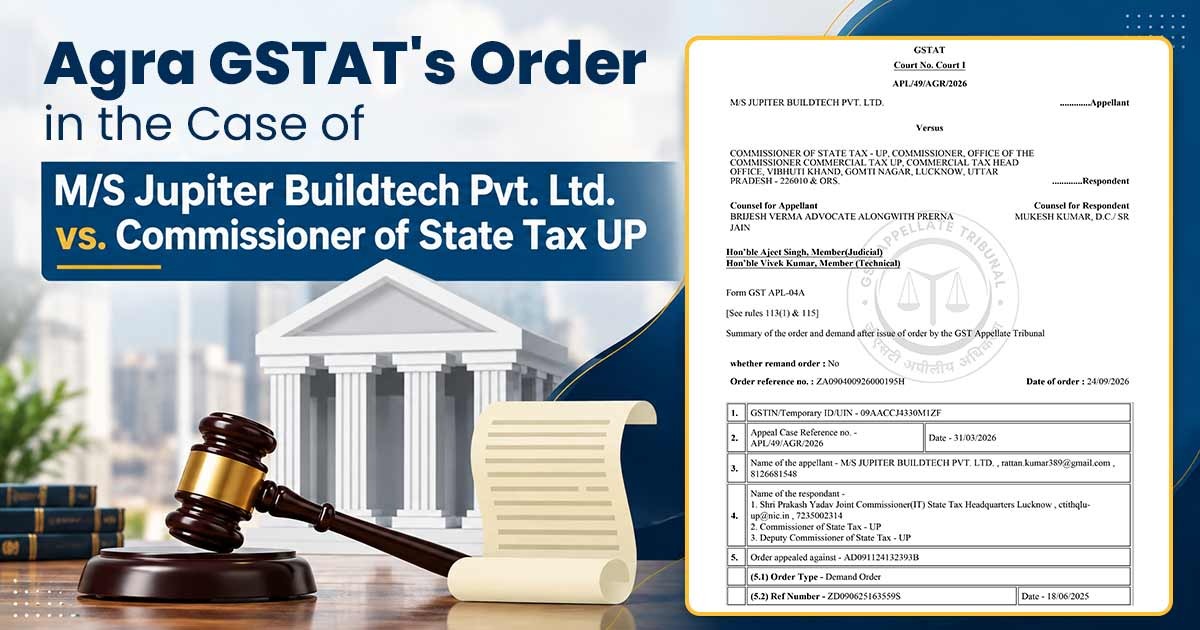
The Agra Bench of the Goods and Services Tax Appellate Tribunal (GSTAT) has held that service tax paid under the erstwhile Finance Act, 1994 on flat bookings subsequently cancelled during the GST regime cannot be claimed as Input Tax Credit (ITC) under the CGST/UPGST Act, 1917.
Jupiter Buildtech Pvt. Ltd. (the appellant) received advances totalling ₹1,28,80,050 for the booking of 10 residential flats. The company collected and deposited service tax of ₹3,82,350 on these advances.
During 2018-19 and 2019-20, the buyers cancelled their bookings, following which the appellant refunded the advances along with the service tax collected.
Thereafter, the applicant claimed the refunded service tax amount as ITC in its GST return and adjusted its GST obligation against the credit. The proper officer denied the claim and raised a tax liability of Rs. 3,82,350, a penalty of Rs. 38,235, and interest of Rs. 3,39,401 u/s 73.
The order has been upheld by the first appellate authority, which said that even if the service tax was refundable, it could not be claimed as GST ITC and should be dealt with u/s 142(5) of the CGST Act.
Counsel for the appellant claimed that the service tax became refundable upon the cancellation of bookings during the GST transition period, and this right should not be denied due to procedural technicalities.
He contended that the adjustment was revenue-neutral, there was no bar under Section 142(5) against making such an adjustment, and the appellate authority had exceeded the scope of the ‘show-cause notice’ in its action.
He further pointed out that when the flats were subsequently resold, a sum of ₹36.30 lakh was paid as CGST and SGST.
Important: UPRERA Outlines Clear Path for Homebuyers to Reclaim GST on Cancelled Flats
The counsel for the revenue stated that service tax filed before GST is not Input tax under the CGST/SGST Act. They added that Section 142(5) furnishes the refund procedure and that a taxpayer cannot build its own procedure for refund by claiming the amount as ITC.
The Bench, Ajeet Singh (Judicial Member) and Vivek Kumar (Technical Member), stated that,
“In our view, the service tax deposited by the taxpayer under the existing Act, i.e. Finance Act, 1994, is not input tax and hence its credit is not allowed as input tax credit.”
Thereafter, the tribunal said that
“The taxpayer cannot avail input tax credit as a mode of refund under the Finance Act 1994, and the amount of service tax previously deposited cannot be claimed as input tax credit in GST returns. Taxpayer can not adopt his own mechanism which is not supported by Law.”
Read Also: GSTAT: ITC Can’t Be Denied Solely Due to GSTR-2A Mismatch Without Invoice-Wise Verification
The Tribunal maintained the earlier appellate order and dismissed the appeal. The Tribunal held that refundable service tax paid under the erstwhile Finance Act, 1994, cannot be claimed as GST ITC.
| Case Title | M/S Jupiter Buildtech Pvt. Ltd. vs. Commissioner of State Tax UP |
| Case No. | APL/49/AGR/2026 |
| Counsel for Appellant | Brijesh Verma and Prerna Jain |
| Counsel for Respondent | Mukesh Kumar |
| Agra GSTAT | Read Order |